10 Best Rated Rewards Credit Cards in 2026
The best rewards credit cards in 2026 can turn ordinary spending on groceries, restaurants, gasoline, travel, entertainment, streaming services, online shopping, transportation, and everyday purchases into valuable cash back, points, or travel miles, making the right rewards card one of the most useful financial tools for consumers who regularly pay their balances in full. Today’s strongest rewards credit cards range from premium travel cards offering airport lounge access and transferable points to no-annual-fee cash back cards that provide straightforward rewards on virtually every purchase, and the best choice depends heavily on how much a cardholder spends, which categories dominate the household budget, whether the rewards will primarily be used for travel or cash back, and whether the benefits can justify an annual fee. Our 2026 ranking compares 10 of the best rated rewards credit cards based on overall reward potential, welcome bonuses, ongoing earning rates, annual fees, introductory APRs, regular APRs, travel benefits, redemption flexibility, foreign transaction costs, category limitations, simplicity, transfer opportunities, and long-term value.
Important Note About Rewards Credit Card Offers in 2026
Rewards credit card offers can change throughout 2026, including welcome bonuses, spending requirements, annual fees, introductory APR periods, variable APR ranges, statement credits, transfer partners, travel benefits, reward categories, spending caps, merchant eligibility rules, and other account terms, and individual applicants may occasionally receive targeted or personalized offers that differ from generally advertised promotions. Consumers should therefore review the final pricing and benefits presented during the application process before opening an account, particularly when a card carries an annual fee or when the expected first-year value depends heavily on earning a welcome bonus. Rewards should also generally be treated as a benefit for purchases that would have been made anyway rather than an incentive to overspend because interest charges on a carried balance can easily exceed the value generated by even a strong 2%, 3%, 5%, or higher rewards rate.
What Are the Best Rewards Credit Cards in 2026?
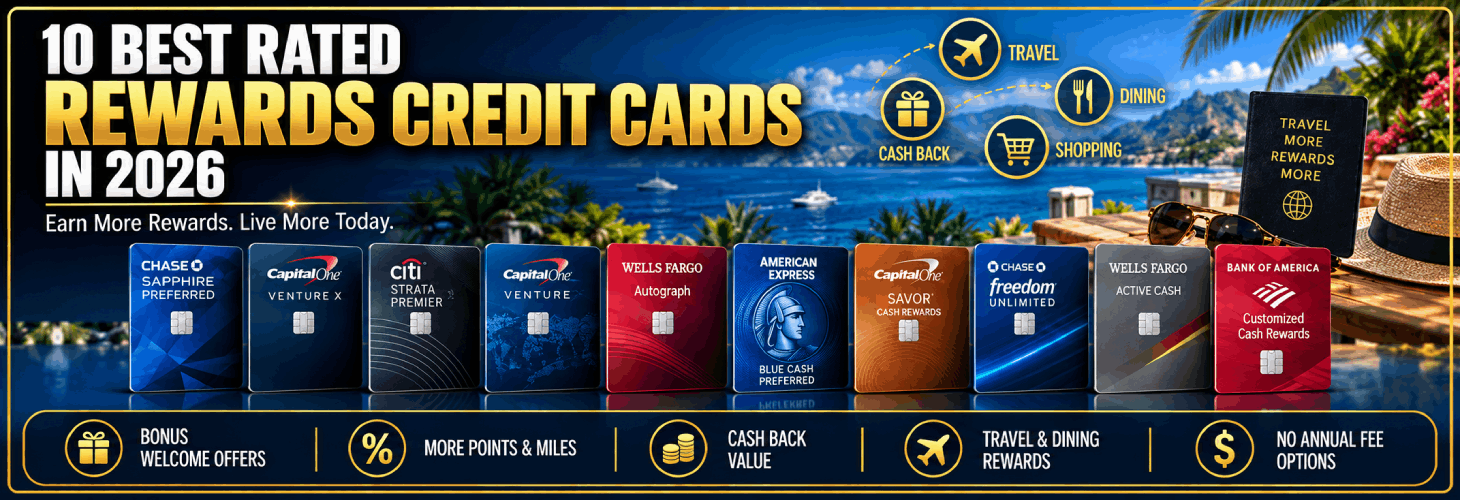
The Chase Sapphire Preferred® Credit Card ranks as our best overall rewards credit card for 2026 because it combines a comparatively manageable annual fee with flexible Ultimate Rewards points, strong travel and dining categories, valuable transfer partners, a substantial introductory bonus, useful travel protections, and multiple redemption choices. Capital One Venture X Rewards ranks second for premium travelers who can maximize its travel benefits and airport lounge access, while Citi Strata Premier® is one of the strongest choices for earning transferable rewards across restaurants, supermarkets, gas stations, airfare, and hotels. Capital One Venture Rewards offers uncomplicated 2X earning, Wells Fargo Autograph® provides unusually broad 3X categories without an annual fee, Blue Cash Preferred® from American Express remains especially powerful for supermarket and streaming purchases, Capital One Savor is excellent for dining and entertainment, Chase Freedom Unlimited® combines elevated bonus categories with dependable everyday rewards, Wells Fargo Active Cash® delivers an uncomplicated unlimited 2% cash rewards structure, and Bank of America® Customized Cash Rewards completes the ranking with flexible category selection and an especially strong first-year category bonus.
How We Rated the Best Rewards Credit Cards
Each card in this ranking was evaluated according to the amount of practical value it can deliver to a typical cardholder rather than simply ranking cards by the highest advertised reward percentage, because a 10X portal category that a consumer rarely uses can ultimately generate less value than an unlimited 2X or 2% earning rate applied to thousands of dollars of ordinary spending. Our methodology considers ongoing earning potential, the usefulness of bonus categories, introductory offers, annual fees, introductory APRs, standard variable APRs, travel credits, foreign transaction fees, redemption options, point-transfer opportunities, spending caps, reward expiration policies, travel protections, convenience, and whether the card remains valuable after the first-year promotion ends. We also place significant weight on whether consumers can realistically recover an annual fee through ordinary use, whether rewards remain competitive outside specialty categories, and how much effort is required to activate categories, use travel portals, track credits, or maximize transfer partners.
Favorable Aspects of the Best Rewards Credit Cards
- Substantial welcome bonuses: Several leading rewards cards can provide hundreds of dollars or potentially considerably more in first-year travel or redemption value after the required introductory spending is completed.
- Strong everyday earning categories: Rewards can be earned on common household spending including supermarkets, restaurants, gasoline, travel, transit, entertainment, streaming services, drugstores, hotels, airfare, and online purchases.
- Flat-rate rewards options: Consumers who do not want to track categories can choose cards offering approximately 1.5%, 2%, or 2X rewards across virtually all eligible purchases.
- Transferable points and miles: Several major rewards programs allow points or miles to be transferred to participating airline and hotel loyalty programs, creating opportunities for greater travel value.
- No annual fee choices: Consumers do not necessarily need a premium card to earn competitive rewards because several products in this ranking charge no annual fee.
- Travel benefits: Premium and mid-tier cards may include travel credits, airport lounge access, rental-car coverage, baggage protections, trip insurance, or other valuable travel features.
- Introductory APR promotions: Several cards provide temporary 0% introductory APR offers that can add financing flexibility during the first year.
- Flexible redemption choices: Rewards may be usable for travel, statement credits, cash back, gift cards, eligible purchases, or transfers to participating travel programs.
- No foreign transaction fees on selected cards: Travelers can avoid the common foreign transaction surcharge with several of the highest-ranked options.
- Long-term reward value: The strongest cards remain competitive after their initial welcome offers expire because their ongoing earning rates can continue producing meaningful value year after year.
Unfavorable Aspects of Rewards Credit Cards
- Annual fees can reduce net rewards: Premium rewards cards can charge significant annual fees, requiring cardholders to actively use their benefits to justify ownership.
- Welcome bonuses require substantial spending: Some of the most valuable introductory offers require several thousand dollars of qualifying purchases within only a few months.
- High standard APRs: Carrying an interest-bearing balance can erase far more value than a cardholder receives from rewards.
- Bonus categories may have spending caps: Some cards limit how much spending qualifies for their highest earning rate.
- Travel portals may be necessary: Certain elevated travel reward rates or annual travel credits require bookings through an issuer-operated portal.
- Point values can vary: Flexible points and travel miles may be worth different amounts depending on the redemption method.
- Transfer programs require additional knowledge: Maximizing airline and hotel transfers can require more time and planning than redeeming simple cash back.
- Merchant classifications matter: A purchase that appears to fit a bonus category may not qualify if the merchant processes the transaction under a different category code.
- Foreign transaction fees remain on some cash back cards: Consumers traveling internationally should check fees before relying on a particular rewards card abroad.
- Overspending defeats the purpose: Buying unnecessary items simply to earn a bonus or additional rewards can eliminate the financial advantage of the program.
1. Chase Sapphire Preferred® Credit Card – Best Overall Rewards Credit Card

The Chase Sapphire Preferred® Credit Card earns the number-one position among the best rewards credit cards in 2026 because its combination of flexible rewards, valuable travel redemption opportunities, useful spending categories, travel protections, and a manageable $95 annual fee makes it suitable for a much broader audience than many premium travel cards. New cardmembers can currently earn 75,000 bonus points after spending $5,000 on purchases within the first three months, creating substantial first-year potential for consumers who can comfortably meet the spending requirement without increasing their normal budget. The card earns 5X points on qualifying Chase Travel purchases, 3X on dining, select streaming services, and qualifying online grocery purchases, 2X on other travel, and 1X on most remaining purchases. Ultimate Rewards points can be particularly valuable because eligible cardholders can redeem through Chase and transfer points to participating airline and hotel loyalty programs, providing flexibility that straightforward cash-back cards cannot match. Sapphire Preferred also avoids foreign transaction fees, making it considerably more useful internationally than many cash-back alternatives, although consumers primarily interested in simple rewards rather than travel may prefer a no-annual-fee option.
Chase Sapphire Preferred® Card Facts Table
| Feature | Details |
| Credit Card Issuer | JPMorgan Chase Bank, N.A. |
| Payment Network | Visa Signature® |
| Rewards Type | Travel Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Rewards Program | Chase Ultimate Rewards® |
| Welcome Offer | 75,000 bonus points after $5,000 in purchases within 3 months |
| Chase Travel Rewards | 5X points |
| Dining Rewards | 3X points |
| Gas Station Rewards | 3X points |
| EV Charging Rewards | 3X points |
| Vacation Home Rewards | 3X points at qualifying top brands |
| Online Grocery Rewards | 3X points, exclusions apply |
| Streaming Rewards | 3X points on eligible services |
| Other Travel Rewards | 2X points |
| General Purchases | 1X point |
| Lyft Rewards | 5X total points through September 30, 2027 |
| Peloton Rewards | 5X total points on qualifying purchases through December 31, 2027 |
| Annual Fee | $95 |
| Authorized-User Annual Fee | $0 |
| Intro Purchase APR | None |
| Regular Purchase APR | 19.24%–27.49% variable |
| Intro Balance Transfer APR | None |
| Foreign Transaction Fee | $0 |
| Annual Chase Travel Hotel Credit | Up to $100 each account anniversary year |
| Global Entry/TSA PreCheck/NEXUS Credit | Up to $120 every 4 years |
| Travel Transfer Partners | Yes |
| Points Boost | Up to 1.5X value on qualifying Chase Travel offers |
| Airport Lounge Membership | Not included |
| Primary Rental Car Coverage | Yes, on qualifying rentals |
| Trip Cancellation/Interruption Insurance | Up to $10,000 per covered traveler and $20,000 per trip |
| Trip Delay Coverage | Up to $500 per covered traveler after qualifying delay |
| Baggage Delay Coverage | Up to $100 per day for up to 5 days |
| Emergency Evacuation Coverage | Up to $100,000 on qualifying trips |
| Travel Accident Insurance | Up to $500,000 |
| Purchase Protection | Up to $500 per eligible item for qualifying damage or theft |
| DoorDash Benefits | Available under current promotional terms |
| Apple TV Benefit | One complimentary year when activated by December 31, 2026 |
| 10% Anniversary Bonus for New Applicants | Discontinued for applications on or after June 15, 2026 |
| Best For | Flexible travel rewards, transferable points, dining and travel benefits |
Why Chase Sapphire Preferred Ranks First
Chase Sapphire Preferred ranks first because it occupies an unusually attractive middle ground between basic no-fee rewards cards and increasingly expensive premium travel products, allowing consumers to access a sophisticated transferable-points ecosystem without paying several hundred dollars every year. The welcome bonus can create substantial immediate value, while dining, travel, streaming, and online grocery earning categories cover several recurring household expenses. More importantly, points can remain useful even if travel habits change because redemption opportunities extend beyond a single airline or hotel brand. Consumers who travel often enough to appreciate transfer partners but not enough to justify a luxury annual fee may find Sapphire Preferred one of the most balanced long-term rewards cards available in 2026.
2. Capital One Venture X Rewards Credit Card – Best Premium Rewards Credit Card

The Capital One Venture X Rewards Credit Card ranks second and is our preferred premium rewards option because it combines an easy-to-understand 2X base earning rate with significantly elevated travel rewards, airport lounge benefits, transferable miles, and valuable annual travel features for a $395 annual fee. Cardholders earn 10X miles on hotels and rental cars booked through Capital One Travel, 5X on flights and vacation rentals booked through Capital One Travel, and unlimited 2X miles on most other purchases, allowing the card to function effectively as both a premium travel product and a general spending card. Eligible primary cardholders can access Capital One Lounge and Landing locations as well as participating Priority Pass lounges after enrollment, while miles can be transferred to more than 15 participating travel loyalty programs. Venture X also has no foreign transaction fee and provides cell phone protection and other travel-related features. The $395 annual fee is substantial, however, and consumers who travel only occasionally should calculate the realistic value of the benefits they will actually use rather than assuming every advertised perk offsets the fee.
Capital One Venture X Rewards Card Facts Table
| Feature | Details |
| Credit Card Issuer | Capital One |
| Payment Network | Mastercard |
| Rewards Type | Travel Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $395 |
| Rewards | 10x portal hotels and rental cars; 5x portal flights and vacation rentals; 2x other purchases |
| Welcome Bonus | 75,000 miles after $4,000 in purchases within 3 months |
| Intro APR | None advertised |
| Regular APR | 19.49%–28.49% variable |
| Balance Transfer Fee | Current transfer APR and any applicable fee are shown in the application disclosure |
| Foreign Transaction Fee | $0 |
| Best For | Premium travel benefits with simple 2x everyday miles |
| Notable Benefits | $300 annual portal travel credit, 10,000 anniversary miles, lounges, transfer partners and up to $120 trusted-traveler credit |
Why Capital One Venture X Ranks Second
Venture X ranks second because it provides premium benefits without sacrificing the simplicity that makes flat-rate rewards cards attractive, as earning 2X miles on ordinary purchases eliminates the need to remember multiple everyday bonus categories. Consumers who regularly use Capital One Travel can increase their earning rate substantially on hotels, rental cars, flights, and vacation rentals, and transfer partners provide opportunities to pursue greater value from miles. The principal limitation is that many of its most valuable travel features are relevant only to people who travel enough to use them, so the card is considerably less compelling for households that take infrequent trips.
3. Citi Strata Premier® Credit Card – Best for Everyday Transferable Points

The Citi Strata Premier® Credit Card ranks third because its bonus structure covers an unusually strong collection of both travel and everyday categories for a card with a $95 annual fee. Cardholders earn 10X ThankYou Points on eligible hotels, car rentals, and attractions booked through Citi Travel, 3X on air travel, other hotel purchases, restaurants, supermarkets, gas stations and EV charging stations, and 1X on most other purchases. The breadth of its 3X categories means a household can accumulate significant rewards from expenses that occur every week rather than relying exclusively on occasional travel purchases. New cardmembers can currently earn 60,000 ThankYou Points after spending $4,000 during the first three months, and the card includes a $100 annual hotel benefit on an eligible hotel stay of $500 or more booked through Citi Travel. The lack of foreign transaction fees also increases its usefulness internationally, while transferable ThankYou Points provide considerably greater flexibility than a proprietary fixed-value travel currency.
Citi Strata Premier® Card Facts Table
| Feature | Details |
| Credit Card Issuer | Citibank, N.A. |
| Payment Network | Mastercard® |
| Rewards Type | Travel Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $95 |
| Citi Travel Rewards | 10X on eligible hotels, car rentals and attractions booked through Citi Travel |
| Bonus Rewards | 3X on air travel, other hotel purchases, restaurants, supermarkets, gas stations and EV charging |
| Other Purchases | 1X ThankYou Point |
| Welcome Bonus | 60,000 ThankYou Points after $4,000 in qualifying purchases within the first 3 months |
| Intro Purchase APR | None advertised |
| Regular APR | 20.24%–28.24% variable |
| Balance Transfer Fee | Either $5 or 5% of each transfer, whichever is greater |
| Foreign Transaction Fee | $0 |
| Annual Hotel Benefit | $100 off one qualifying $500+ hotel stay booked through Citi Travel each calendar year |
| Best For | Flexible travel rewards and everyday bonus categories |
| Notable Benefits | ThankYou transfer partners, annual hotel benefit, no foreign transaction fee and Citi travel benefits |
Why Citi Strata Premier Ranks Third
Citi Strata Premier ranks third because few mid-tier travel cards provide bonus rewards across such a useful combination of supermarkets, restaurants, gasoline, EV charging, airfare, and hotels while maintaining a relatively modest annual fee. Someone who spends heavily in those categories can accumulate ThankYou Points quickly even during months without major travel expenses, and transferring those points to participating travel partners can make the rewards program significantly more flexible. Its principal weaknesses are the 1X rate on purchases outside the bonus categories and the requirement to use Citi Travel for the highest hotel, rental-car, attraction, and annual hotel-benefit value.
4. Capital One VentureOne Rewards Credit Card – Best for Simple Travel Miles
The Capital One VentureOne Rewards Credit Card earns fourth place because its unlimited 2X miles structure provides a simple approach to travel rewards for consumers who want transferable miles without managing several purchase categories. The card currently features a particularly attractive limited-time offer providing $300 to use toward hotel and vacation-rental bookings through Capital One Travel during the first cardholder year in addition to 75,000 bonus miles after $4,000 in purchases during the first three months, creating potentially significant first-year travel value for eligible new cardholders. Ongoing rewards include unlimited 2X miles on everyday purchases and 5X miles on hotels, vacation rentals, and rental cars booked through Capital One Travel. The $95 annual fee is considerably less expensive than premium cards, the card charges no foreign transaction fee, and eligible cardholders can receive up to a $120 statement credit toward Global Entry or TSA PreCheck. Miles can also be transferred to more than 15 participating travel loyalty programs, making the card considerably more versatile than a simple fixed-value travel product.
Capital One VentureOne Card Facts Table
| Feature | Details |
| Credit Card Issuer | Capital One |
| Payment Network | Mastercard |
| Reward Type | Travel Rewards Credit Card |
| Recommended Credit Score | Good to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Security Deposit | None |
| Standard Rewards | Unlimited 1.25X miles per dollar on eligible purchases |
| Bonus Rewards | 5X miles on eligible hotels, vacation rentals, rental cars and activities through Capital One Travel; 5X miles on qualifying Capital One Entertainment purchases |
| Welcome Bonus | 20,000 miles after $500 in purchases within 3 months of account opening for eligible applicants |
| Intro APR | 0% introductory APR on purchases and balance transfers for 15 months |
| Regular APR | 18.49%–28.49% variable APR after the introductory period, based on creditworthiness |
| Balance Transfer Fee | 3% on transferred amounts during the first 15 months; later promotional transfers may carry a 4% fee |
| Cash Advance Fee | 5% of the advance, with a $5 minimum |
| Foreign Transaction Fees | None |
| Credit Bureau Reporting | Account activity is generally reported to Equifax, Experian and TransUnion |
| Credit Line Increases | May be available after account review; not guaranteed |
| Best For | Occasional travelers seeking flexible miles, introductory APR value and no annual fee |
| Employee Cards | Not applicable to this consumer card; authorized users may be added |
Why Capital One Venture Rewards Ranks Fourth
Capital One Venture Rewards ranks fourth because it gives consumers much of the flexibility associated with sophisticated travel programs while maintaining one of the easiest reward calculations in the category: most eligible spending earns 2X miles. This makes it especially appealing to households with substantial expenses that do not fall naturally into traditional bonus categories. The current first-year promotion significantly strengthens its value, and transfer partners increase the potential usefulness of accumulated miles, although consumers primarily interested in cash back can obtain similar or better straightforward returns from no-annual-fee cards.
5. Wells Fargo Autograph® Credit Card – Best No Annual Fee Points Rewards Card
The Wells Fargo Autograph® Credit Card ranks fifth and is one of the strongest no-annual-fee rewards cards in 2026 because it earns unlimited 3X points across restaurants, travel, gas stations, EV charging, transit, popular streaming services, and eligible phone plans while charging no foreign transaction fee. Those categories cover a remarkably broad range of recurring expenses for a card that costs nothing annually to retain. New cardholders can earn 20,000 bonus points after making $1,000 in purchases during the first three months, representing a $200 cash redemption value under standard Wells Fargo redemption terms, and the card currently includes a 0% introductory APR on purchases for 12 months from account opening before the regular variable APR applies. Eligible cardholders can also access Wells Fargo travel-transfer partners, cell phone protection, rental-car coverage, Visa Signature benefits, and other features. General purchases outside the 3X categories earn only 1X, making the card most effective when combined with a strong flat-rate rewards card.
Wells Fargo Autograph® Card Facts Table
| Feature | Details |
| Credit Card Issuer | Wells Fargo Bank, N.A. |
| Payment Network | Visa Signature |
| Reward Type | 0% Intro APR – Customized Cash Rewards |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Rewards | Unlimited 3X restaurants, travel, gas, EV charging, transit, popular streaming services and phone plans; 1X other qualifying purchases |
| Welcome Bonus | 20,000 bonus points after $1,000 in qualifying purchases within the first 3 months |
| Welcome Bonus Cash Value | $200 cash redemption value |
| Intro Purchase APR | 0% for 12 months from account opening |
| Regular Purchase APR | 18.49%, 24.49% or 28.49% variable APR |
| Balance Transfer APR | 18.49%, 24.49% or 28.49% variable APR |
| Balance Transfer Fee | $5 or 3%, whichever is greater, during the first 120 days; after that up to 5%, minimum $5 |
| Cash Advance Fee | $10 or 5%, whichever is greater |
| Foreign Transaction Fee | $0 |
| Best For | No-annual-fee travel, dining, gas, transit and everyday bonus rewards |
| Notable Benefits | Cell phone protection, rental car coverage, travel assistance, Visa Signature benefits, transfer partners and no foreign transaction fee |
Why Wells Fargo Autograph Ranks Fifth
Wells Fargo Autograph ranks fifth because charging no annual fee while simultaneously providing unlimited 3X rewards across travel, restaurants, gasoline, transit, phone plans, streaming, and EV charging is an unusually competitive combination. International travelers also benefit from the absence of foreign transaction fees, while the introductory APR promotion gives the account additional first-year utility. Autograph would rank even higher if its base rate were stronger than 1X, but pairing it with a 2% flat-rate card can create an effective strategy that captures elevated rewards across a large percentage of everyday spending.
6. Blue Cash Preferred® Credit Card from American Express – Best for Groceries and Streaming
The Blue Cash Preferred® Credit Card from American Express ranks sixth because it remains one of the most rewarding cash-back cards available for households that spend heavily at U.S. supermarkets and on eligible streaming subscriptions. Cardholders earn 6% cash back at U.S. supermarkets on up to $6,000 in qualifying purchases per year before the rate becomes 1%, unlimited 6% on select U.S. streaming subscriptions, 3% at eligible U.S. gas stations, 3% on qualifying transit, and 1% on other eligible purchases. American Express currently advertises personalized introductory offers that can be as high as $300 cash back after $3,000 in qualifying purchases during the first six months, although individual offers may vary. The annual fee is currently $0 during the introductory first year and then $95, while a 0% introductory APR promotion on purchases and qualifying balance transfers for 12 months can add additional first-year value. The biggest limitation is the $6,000 annual supermarket spending cap and the 2.7% foreign transaction fee.
Blue Cash Preferred® Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Cash Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 introductory annual fee for the first year, then $95 |
| Security Deposit | None |
| Standard Rewards | 1% cash back on other eligible purchases |
| Bonus Rewards | 6% at U.S. supermarkets on up to $6,000 per calendar year, then 1%; 6% on select U.S. streaming subscriptions; 3% at eligible U.S. gas stations and on transit |
| Welcome Bonus | Personalized offer as high as $300 cash back after $3,000 in purchases within six months; offers vary and some applicants may receive a lower offer or none |
| Intro APR | 0% introductory APR on purchases and eligible balance transfers for 12 months from account opening; transfers must generally be requested within the first 60 days |
| Regular APR | 19.49%–28.49% variable APR after the introductory period, based on creditworthiness and subject to change |
| Balance Transfer Fee | Either $5 or 3% of each transferred amount, whichever is greater |
| Cash Advance Fee | Either $10 or 5% of each cash advance, whichever is greater |
| Foreign Transaction Fees | 2.7% of each transaction after conversion to U.S. dollars |
| Credit Bureau Reporting | Account activity is generally reported to Equifax, Experian and TransUnion |
| Credit Line Increases | May be requested or offered after review; approval and the amount are not guaranteed |
| Best For | Households with substantial U.S. supermarket, streaming, gas and transit spending that can offset the annual fee |
| Employee Cards | Not applicable to this consumer card; Additional Card Members may be added subject to account terms |
Why Blue Cash Preferred Ranks Sixth
Blue Cash Preferred ranks sixth because few rewards cards can match a 6% return on two spending areas as common as supermarkets and eligible streaming services, and a household maximizing the $6,000 supermarket limit could generate $360 in grocery rewards alone before accounting for streaming, gasoline, transit, welcome-offer value, or other benefits. The card is less attractive for consumers who shop primarily at superstores or warehouse clubs, spend far beyond the supermarket cap, or frequently travel internationally, but for the right household budget its category returns can easily justify the ongoing annual fee.
7. Capital One Savor Cash Rewards Credit Card – Best for Dining and Entertainment
The Capital One Savor Cash Rewards Credit Card ranks seventh because its reward categories are strongly aligned with everyday lifestyle spending and it charges neither an annual fee nor foreign transaction fees. New cardholders can currently earn a $200 cash bonus after spending $500 on purchases within the first three months, and the card offers 0% introductory APR financing for 12 months on purchases and balance transfers before a regular variable APR applies. Cardholders earn unlimited 3% cash back at qualifying grocery stores, on dining, entertainment, and popular streaming services, 5% on hotels, vacation rentals, and rental cars booked through Capital One Travel, and 1% on most other purchases. The combination is especially appealing to consumers who regularly dine out, attend concerts or sporting events, subscribe to multiple streaming platforms, and spend substantially at grocery stores. Rewards do not expire while the account remains open, and the absence of an annual fee makes the card easy to retain long term.
Capital One Savor Card Facts Table
| Feature | Details |
| Credit Card Issuer | Capital One |
| Payment Network | Mastercard |
| Reward Type | Cash Back Credit Card |
| Recommended Credit Score | Good to Excellent Credit Score (690-850) |
| Annual Fee | $0 for the current public offer |
| Security Deposit | None |
| Standard Rewards | Unlimited 1% cash back on eligible purchases outside bonus categories |
| Bonus Rewards | 3% at eligible grocery stores and on dining, entertainment and popular streaming; 5% on eligible Capital One Travel bookings; 8% on qualifying Capital One Entertainment purchases |
| Welcome Bonus | $200 after $500 in purchases within 3 months of account opening for eligible applicants |
| Intro APR | 0% introductory APR on purchases and balance transfers for 12 months |
| Regular APR | 18.49%–28.49% variable APR after the introductory period, based on creditworthiness |
| Balance Transfer Fee | 3% on transferred amounts during the first 12 months; later promotional transfers may carry a 4% fee |
| Cash Advance Fee | 5% of the advance, with a $5 minimum |
| Foreign Transaction Fees | None |
| Credit Bureau Reporting | Account activity is generally reported to Equifax, Experian and TransUnion |
| Credit Line Increases | May be available after account review; not guaranteed |
| Best For | Food-focused households, frequent diners, entertainment buyers and streaming subscribers seeking no-annual-fee cash back |
| Employee Cards | Not applicable to this consumer card; authorized users may be added |
Why Capital One Savor Ranks Seventh
Capital One Savor ranks seventh because a $0 annual fee and unlimited 3% cash back across several major household spending categories create excellent long-term economics without requiring cardholders to offset a membership charge. The $200 introductory bonus has a comparatively manageable spending requirement, and the introductory APR further improves first-year value. Its principal weakness is the ordinary 1% earning rate on purchases outside the featured categories, which means consumers with significant uncategorized spending may want to pair it with a 2% flat-rate card.
8. Chase Freedom Unlimited® Credit Card – Best Hybrid Everyday Rewards Card

The Chase Freedom Unlimited® Credit Card ranks eighth because it combines a higher-than-standard base earning rate with permanent dining, drugstore, and Chase Travel bonus categories while charging no annual fee. Cardholders earn 5% cash back on qualifying travel purchased through Chase Travel, 3% on dining including eligible takeout and delivery, 3% at drugstores, and unlimited 1.5% on most remaining purchases. New cardholders can earn a $200 bonus after spending $500 on purchases during the first three months, and the card currently includes 0% introductory APR financing for 15 months on purchases and balance transfers before a variable APR of 18.24%–27.74% applies. Although rewards are marketed as cash back, they are generated within the Chase Ultimate Rewards ecosystem, making Freedom Unlimited particularly valuable for consumers who also hold an eligible premium Chase rewards card and can combine points for additional travel options.
Chase Freedom Unlimited® Card Facts Table
| Feature | Details |
| Credit Card Issuer | JPMorgan Chase Bank, N.A. |
| Payment Network | Visa |
| Card Type | Cash Back Rewards Credit Card – 0% Intro APR Credit Card |
| Recommended Credit Score | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Intro Offer | $200 Bonus |
| Intro Offer Requirement | $500 in purchases within first 3 months |
| Bonus Form | 20,000 Ultimate Rewards points redeemable for $200 cash back |
| Authorized User Annual Fee | $0 |
| Chase Travel Rewards | 5% Cash Back |
| Dining Rewards | 3% Cash Back |
| Drugstore Rewards | 3% Cash Back |
| Lyft Rewards | 2% total on qualifying purchases through September 30, 2027 |
| Other Eligible Purchases | Unlimited 1.5% Cash Back |
| Rewards Currency | Chase Ultimate Rewards Points |
| Rewards Expiration | No expiration while eligible account remains open |
| Minimum Cash Redemption | None |
| Intro Purchase APR | 0% for 15 months |
| Intro Balance Transfer APR | 0% for 15 months |
| Regular Purchase APR | 18.24%–27.74% Variable |
| Regular Balance Transfer APR | 18.24%–27.74% Variable |
| Intro Balance Transfer Fee | $5 or 3%, whichever is greater, during applicable introductory window |
| Regular Balance Transfer Fee | $5 or 5%, whichever is greater |
| Foreign Transaction Fee | 3% |
| Purchase Protection | Up to $500 per eligible item for 120 days |
| Extended Warranty | Additional year on eligible warranties |
| Trip Cancellation/Interruption | Up to $1,500 per traveler and $6,000 per covered trip |
| Auto Rental Coverage | Theft and collision protection on eligible rentals |
| DoorDash | Eligible promotional DashPass and quarterly discount benefits |
| Annual Fee | $0 |
| Best For | Everyday cash back, dining, drugstores, Chase Travel, and introductory financing |
Why Chase Freedom Unlimited Ranks Eighth
Freedom Unlimited ranks eighth because its 1.5% minimum reward rate produces more value on miscellaneous purchases than the traditional 1% base rate while its 3% dining and drugstore categories provide additional earning opportunities. The introductory bonus and lengthy 0% APR period increase its first-year appeal, and combining the card with Sapphire Preferred or another eligible Chase product can make its points significantly more strategically useful. Consumers focused solely on flat-rate cash back, however, can find cards paying 2% on general purchases, which prevents Freedom Unlimited from ranking higher by itself.
9. Wells Fargo Active Cash® Credit Card – Best Flat-Rate Cash Rewards Card

The Wells Fargo Active Cash® Credit Card ranks ninth but remains one of the easiest rewards cards to recommend to consumers who prioritize simplicity because it earns unlimited 2% cash rewards on eligible purchases without requiring category activation, spending caps, merchant tracking, or travel bookings. The card has no annual fee, and new cardholders currently may earn a $100 cash rewards bonus after spending $500 in purchases during the first three months. It also provides a 0% introductory APR for 12 months from account opening on purchases and qualifying balance transfers before an 18.49%, 24.49%, or 28.49% variable APR applies. Additional features include eligible cell phone protection of up to $600 per approved claim after the deductible when requirements are satisfied, rental-car coverage, Visa Signature privileges, and Wells Fargo merchant offers. The principal weakness for travelers is its 3% foreign transaction fee, which makes other cards in this ranking better choices outside the United States.
Wells Fargo Active Cash® Card Facts Table
| Feature | Details |
| Credit Card Issuer | Wells Fargo Bank, N.A. |
| Payment Network | Visa Signature |
| Rewards Type | 0% Intro APR – Customized Cash Rewards |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Rewards | Unlimited 2% cash rewards on qualifying purchases |
| Welcome Bonus | $200 cash rewards after $500 in purchases within the first 3 months |
| Intro Purchase APR | 0% introductory APR for 12 months |
| Intro Balance Transfer APR | 0% introductory APR for 12 months on qualifying balance transfers |
| Regular APR | 18.49%, 24.49%, or 28.49% Variable APR |
| Balance Transfer Fee | Greater of $5 or 3% during the introductory transfer period; afterward up to 5% with a $5 minimum |
| Foreign Transaction Fee | 3% |
| Best For | Simple unlimited flat-rate cash rewards on domestic everyday purchases |
| Notable Benefits | Cell phone protection, flexible rewards redemption, $0 annual fee, digital banking tools, fraud protection |
Why Wells Fargo Active Cash Ranks Ninth
Wells Fargo Active Cash ranks ninth because simplicity has considerable value in a rewards market increasingly filled with complicated categories, monthly credits, travel portals, transfer partners, and activation requirements. A cardholder spending $30,000 annually on eligible purchases could generate approximately $600 in cash rewards without tracking a single category, making the card particularly effective for insurance, home expenses, medical bills, general retail, and other purchases that often earn only 1% elsewhere. It ranks below specialized category cards because consumers with concentrated grocery, dining, or travel spending may earn more by using higher-rate categories, but Active Cash remains an excellent companion card for everything that does not qualify for an elevated rate.
10. Bank of America® Customized Cash Rewards Credit Card – Best for Flexible Bonus Categories
The Bank of America® Customized Cash Rewards Credit Card rounds out our top 10 because it allows consumers to choose the spending category in which they receive their highest rewards and currently provides an unusually strong first-year enhancement. Cardholders earn a standard 3% cash back in a selected category such as gas and EV charging, online shopping including eligible internet, cable, phone plans and streaming, dining, travel, drugstores and pharmacies, or home improvement and furnishings, but during the first year the card currently adds an additional 3% bonus to the selected category for a total of 6%. Grocery stores and wholesale clubs earn 2%, while other purchases earn unlimited 1%. The 6% choice-category rate and 2% grocery/wholesale rate apply to the first $2,500 in combined quarterly purchases in those categories before the rate becomes 1%. New applicants can also earn a $200 online cash rewards bonus after at least $1,000 in purchases within the first 90 days, while a 0% introductory APR for 15 billing cycles on purchases and eligible balance transfers adds additional first-year value.
Bank of America® Customized Cash Rewards Card Facts Table
| Feature | Details |
| Credit Card Issuer | Bank of America, N.A. |
| Payment Network | Visa Signature |
| Reward Type | Cash-Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| First-Year Choice Category | 6% Cash Back |
| Standard Choice Category After First Year | 3% Cash Back |
| Grocery Stores | 2% Cash Back |
| Wholesale Clubs | 2% Cash Back |
| Other Purchases | Unlimited 1% Cash Back |
| Quarterly Spending Limit | $2,500 combined in choice category, grocery stores and wholesale clubs |
| Welcome Bonus | $200 after $1,000 in purchases within 90 days |
| Intro Purchase APR | 0% for 15 billing cycles |
| Intro Balance Transfer APR | 0% for 15 billing cycles on qualifying transfers made within 60 days |
| Regular APR | 17.49%–27.49% Variable |
| Intro Balance Transfer Fee | 3% during first 60 days |
| Standard Balance Transfer Fee | 5% after introductory period |
| Category Changes | Once per calendar month |
| Best For | Consumers who want customizable cash-back categories |
| Notable Benefit | BofA Rewards bonuses can increase eligible cash-back earnings |
Why Bank of America Customized Cash Rewards Ranks Tenth
Customized Cash Rewards ranks tenth because the ability to select and periodically change a preferred bonus category allows consumers to adapt the card to changing spending patterns rather than accepting a permanently fixed reward structure. Its temporary first-year 6% selected-category rate is particularly attractive for online shopping, gasoline, dining, travel, home improvement, or another eligible category where a cardholder expects significant purchases. The primary limitation is the combined $2,500 quarterly spending cap covering the highest category and grocery/wholesale-club earnings, which can reduce value for high spenders, and the standard 1% rate on purchases outside the bonus structure is significantly weaker than a 2% flat-rate alternative.
2026 Best Rewards Credit Cards Comparison Table
| Credit Card | Intro Offer | Rewards Rate | Annual Fee | Intro APR | Regular APR |
| Chase Sapphire Preferred® Card | 75,000 points after $5,000 in 3 months | 1X–5X Points | $95 | None | 19.24%–27.49% variable |
| Capital One Venture X Rewards Card | 75,000 miles after $4,000 in 3 months | 2X–10X Points | $395 | None | 19.49%–28.49% variable |
| Citi Strata Premier® Card | 60,000 points after $4,000 in 3 months | 1X–10X Points | $95 | None | Variable APR |
| Capital One VentureOne Card | 75,000 miles plus current first-year $300 travel promotion | 2X–5X Miles | $95 | None | 19.49%–28.49% variable |
| Wells Fargo Autograph® Card | 20,000 points after $1,000 in 3 months | 1X–3X Points | $0 | 0% for 12 months purchases | 18.49%, 24.49% or 28.49% variable |
| Blue Cash Preferred® Card | Personalized offer as high as $300 | 1%–6% Cashback | $0 first year, then $95 | 0% for 12 months | Approximately 19.49%–28.49% variable |
| Capital One Savor Card | $200 after $500 in 3 months | 1%–5% Cashback | $0 | 0% for 12 months | 18.49%–28.49% variable |
| Chase Freedom Unlimited® Card | $200 after $500 in 3 months | 1.5%–5% Cashback | $0 | 0% for 15 months | 18.24%–27.74% variable |
| Wells Fargo Active Cash® Card | $100 after $500 in 3 months | Unlimited 2% Cashback | $0 | 0% for 12 months | 18.49%, 24.49% or 28.49% variable |
| B ofA® Customized Cash Rewards Card | $200 after $1,000 in 90 days | 1%–6% Cashback 1st year | $0 | 0% for 15 billing cycles | 17.49%–27.49% variable |
Which Rewards Credit Card Is Best for Everyday Spending?
The best rewards card for everyday spending depends on whether the consumer prefers simplicity or category maximization. Wells Fargo Active Cash is particularly effective for uncomplicated everyday purchases because unlimited 2% cash rewards apply without category management, while Capital One Venture Rewards provides unlimited 2X miles for travelers. Consumers willing to manage categories may earn substantially more with Capital One Savor on dining, groceries, entertainment, and streaming, Citi Strata Premier on groceries, restaurants, gas, airfare, and hotels, or Blue Cash Preferred on qualifying supermarkets and streaming. Many consumers can ultimately maximize rewards most effectively by combining a category card with a flat-rate card rather than expecting one product to dominate every purchase.
Which Rewards Credit Card Is Best for Travel?
Chase Sapphire Preferred is our best overall rewards choice for travelers who want transferable points without paying a premium annual fee, while Capital One Venture X is stronger for frequent travelers who prioritize airport lounge access and premium benefits. Capital One Venture Rewards provides a simpler middle-ground approach with 2X miles and a $95 annual fee, and Citi Strata Premier is particularly effective for travelers who also spend heavily on supermarkets, restaurants, gasoline, and EV charging. Consumers should compare not only reward rates but also transfer partners, annual credits, travel protections, foreign transaction fees, portal requirements, and the realistic amount of travel they expect to complete every year.
Which Rewards Credit Card Is Best for Cash Back?
Wells Fargo Active Cash is among the best rewards cards for consumers seeking simple flat-rate cash back because virtually every eligible purchase earns unlimited 2% cash rewards, while Capital One Savor is stronger for consumers whose budgets are concentrated in dining, grocery stores, entertainment, and streaming. Blue Cash Preferred can generate exceptional supermarket rewards for households that can maximize its 6% rate without greatly exceeding the annual spending cap, and Bank of America Customized Cash Rewards allows consumers to select the category that best matches their spending habits. Chase Freedom Unlimited sits between flat-rate and category approaches by providing a 1.5% base rate with higher permanent rewards on dining, drugstores, and qualifying Chase Travel purchases.
Are Annual Fee Rewards Credit Cards Worth It?
An annual fee rewards credit card can be worthwhile when the combination of additional rewards, welcome bonuses, annual credits, travel protections, lounge access, transfer opportunities, and other benefits exceeds the cost of owning the card, but consumers should calculate value based on benefits they would naturally use rather than assigning full face value to every advertised perk. A traveler who regularly uses Venture X lounge access and travel benefits may recover far more than the $395 annual fee, while someone who rarely travels could obtain greater net value from a $0 annual fee card. Similarly, a household maximizing Blue Cash Preferred supermarket rewards may easily justify its post-introductory $95 annual fee, whereas a low grocery spender may be better served by a no-fee alternative.
How Many Rewards Credit Cards Should You Have?
There is no single ideal number of rewards credit cards because the right amount depends on spending habits, credit management ability, annual fees, available credit, and willingness to track several accounts. Some consumers prefer one simple 2% cash-back card, while experienced rewards users may combine a travel card, grocery card, dining card, and flat-rate card so that most purchases receive an elevated return. The important consideration is whether every additional account provides enough incremental value to justify the added complexity and whether all balances can be paid responsibly and on time.
Do Credit Card Rewards Expire?
Many major rewards programs allow points, miles, or cash back to remain available as long as the account stays open and in good standing, but expiration and forfeiture policies vary by issuer and program. Closing an account may result in the loss of unused rewards unless they can first be redeemed, transferred, or combined with another eligible account, and program terms can change. Cardholders accumulating substantial reward balances should periodically review program rules rather than assuming rewards will remain available indefinitely.
Is Cash Back Better Than Travel Points?
Cash back is generally better for consumers who value simplicity, predictable redemption value, and the ability to use rewards for virtually any financial purpose, while transferable travel points can be more valuable for travelers willing to learn airline and hotel loyalty programs and search for high-value redemption opportunities. A $500 cash-back balance is straightforwardly worth approximately $500, whereas a large balance of travel points may produce considerably more or less value depending on the redemption method. Neither approach is universally superior, so consumers should choose the reward system they are actually likely to use effectively.
Should You Carry a Balance to Earn Credit Card Rewards?
Consumers should generally avoid carrying an interest-bearing balance simply to earn rewards because standard credit card APRs are frequently far higher than reward rates. A card paying 2% cash back cannot economically compensate for interest charges approaching 20%, 25%, or more annually on revolving debt. Rewards cards provide their greatest financial benefit when purchases fit within an existing budget and the statement balance can be paid in full by the due date, while introductory 0% APR promotions should still be accompanied by a repayment strategy that eliminates the balance before the promotional period expires.
What Credit Score Is Needed for the Best Rewards Credit Cards?
Many of the strongest rewards cards are primarily targeted toward applicants with good to excellent credit, although approval depends on substantially more than a single credit score. Issuers can consider income, debt obligations, existing accounts, recent credit applications, payment history, utilization, relationship history, and other underwriting criteria when reviewing an application. A credit score in the high 600s or above may place consumers in the broad good-credit range commonly associated with many mainstream rewards cards, while premium cards can be more selective, but no particular score guarantees approval or a specific credit limit or APR.
How to Choose the Best Rewards Credit Card in 2026
Choosing the best rewards credit card in 2026 should begin with an analysis of actual household spending rather than the largest advertised reward percentage. Consumers should total annual spending across groceries, dining, gas, travel, entertainment, streaming, online shopping, transit, and miscellaneous purchases and then estimate how many rewards each prospective card would realistically generate after accounting for category caps and annual fees. Travel-focused users should additionally compare transfer partners, airport benefits, foreign transaction fees, portal requirements, travel credits, insurance protections, and redemption flexibility, while cash-back consumers may place greater weight on simplicity and predictable value. Welcome bonuses can meaningfully increase first-year value, but the strongest long-term card is generally the one whose ongoing rewards continue matching the cardholder’s normal spending after the introductory promotion disappears.
Final Verdict: 10 Best Rated Rewards Credit Cards in 2026
The rewards credit card market in 2026 provides strong choices for virtually every spending style, whether the priority is transferable travel points, airport lounge access, grocery rewards, dining cash back, entertainment purchases, flexible bonus categories, introductory financing, or simple unlimited rewards. Chase Sapphire Preferred® earns our number-one ranking because its $95 annual fee unlocks a combination of transferable Ultimate Rewards points, valuable travel and dining earning opportunities, strong introductory value, useful protections, and redemption flexibility without requiring consumers to commit to the much higher cost of a luxury travel card. Capital One Venture X is our strongest premium alternative, Citi Strata Premier excels across both travel and everyday categories, Capital One Venture Rewards provides one of the easiest transferable-mile structures, and Wells Fargo Autograph demonstrates that consumers can obtain competitive points and travel benefits without paying an annual fee. Blue Cash Preferred, Capital One Savor, Chase Freedom Unlimited, Wells Fargo Active Cash, and Bank of America Customized Cash Rewards each provide compelling advantages for specific spending patterns, which means the best rewards card ultimately depends on where a consumer spends money, how rewards will be redeemed, and whether the household can pay the balance responsibly enough for rewards to remain a genuine financial benefit.