10 Best Rated Cash Back Credit Cards in 2026
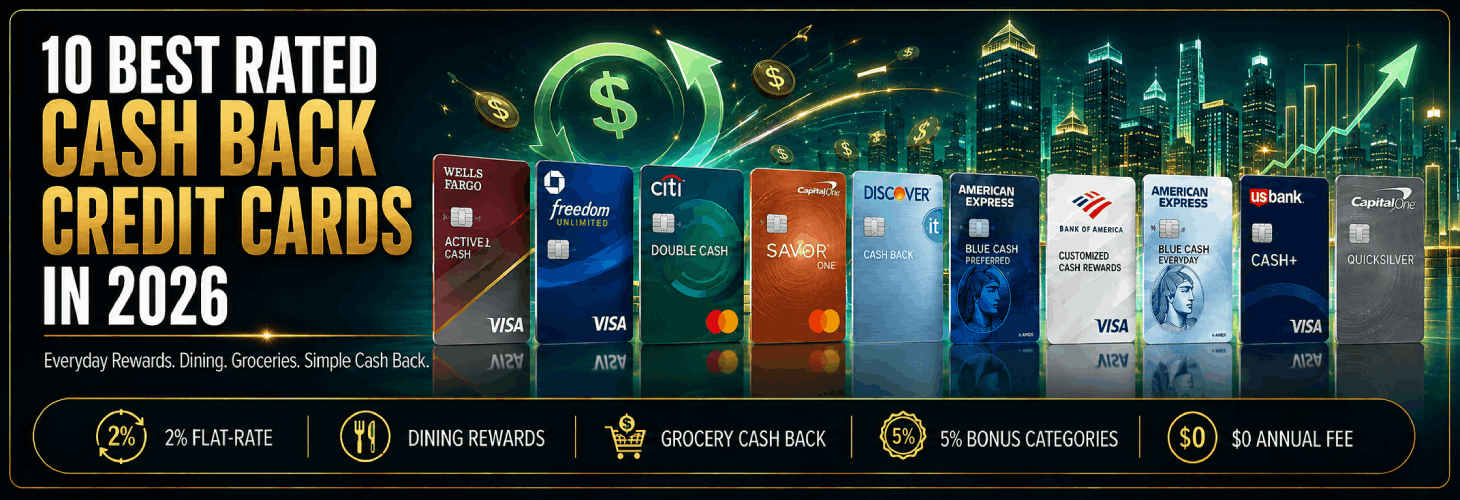
The best cash back credit cards in 2026 give consumers an opportunity to earn meaningful rewards on purchases they already make without relying on complicated airline award charts, hotel transfer programs, or uncertain point valuations, and the strongest cards can return anywhere from approximately 1.5% to 6% or more depending on the spending category and promotional structure. Cash back cards can be particularly valuable for groceries, restaurants, gasoline, online shopping, entertainment, streaming services, drugstores, travel reservations, household expenses, and miscellaneous everyday purchases, while several leading products also combine rewards with $200 or higher introductory bonuses, 0% introductory APR financing, purchase protections, cell phone insurance, statement credits, and other benefits. This 2026 ranking compares 10 leading cash back cards from Wells Fargo, Chase, Citi, Capital One, Discover, American Express, Bank of America, and U.S. Bank according to everyday earning potential, bonus-category usefulness, welcome offers, annual fees, introductory APRs, regular APRs, redemption flexibility, international usability, consumer protections, and long-term value.
Important Note About Cash Back Credit Card Offers
Cash back credit card rewards, introductory bonuses, promotional APR periods, regular variable APRs, balance-transfer fees, annual fees, category spending limits, statement credits, and other benefits can change throughout 2026, and applicants may encounter personalized or targeted offers that differ from broadly advertised terms. A card advertising 5% or 6% cash back does not necessarily earn that rate on every transaction because elevated rewards can be restricted to particular merchant categories or annual and quarterly spending limits, while cards advertising unlimited 2% may provide less upside but considerably greater simplicity. Consumers should also remember that interest charges can easily exceed the value of cash back because carrying a $5,000 balance at an APR above 20% can cost hundreds of dollars per year while 2% cash back on $5,000 of purchases produces only $100 in rewards. Cash back cards therefore provide their greatest financial value when used for purchases already included in a household budget and when statement balances are paid in full whenever possible.
What Are the Best Cash Back Credit Cards in 2026?
The Wells Fargo Active Cash® Card ranks first among the best cash back credit cards in 2026 because it combines unlimited 2% cash rewards with a $200 introductory bonus, a $0 annual fee, 0% introductory financing, cell phone protection, rental car coverage, Visa Signature privileges, and flexible redemption options without requiring cardholders to track bonus categories. Chase Freedom Unlimited® ranks second because it combines unlimited 1.5% base cash back with permanent 3% dining and drugstore rewards and 5% on qualifying Chase Travel purchases, while Citi Double Cash® ranks third with an effective unlimited 2% structure and an extended balance-transfer promotion. Capital One Savor is particularly strong for dining, groceries, entertainment, and streaming, Discover it® Cash Back provides outstanding first-year potential through rotating 5% categories and Unlimited Cashback Match, and Blue Cash Preferred® from American Express remains one of the strongest grocery cards available. Bank of America Customized Cash Rewards, Blue Cash Everyday®, U.S. Bank Cash+, and Capital One Quicksilver round out the Top 10 with customizable categories, online-shopping rewards, selectable 5% categories, and simple international-friendly flat-rate earning.
How We Rated the Best Cash Back Credit Cards
Each cash back card was evaluated on a five-point editorial framework emphasizing the amount of realistic reward value an average consumer can earn rather than simply ranking cards according to their highest advertised percentage. Unlimited flat-rate cards received strong scores when they earned approximately 2% on broad spending without annual caps, while category cards were evaluated according to how useful their elevated categories are for common expenses such as groceries, restaurants, gasoline, streaming, travel, entertainment, and online shopping. We also considered annual fees, introductory bonuses, 0% APR promotions, regular APRs, balance-transfer costs, foreign transaction fees, reward expiration policies, statement credits, consumer protections, redemption simplicity, and whether each card remains useful after the initial welcome offer ends. Cards that require an annual fee were judged according to whether realistic cash-back earnings and benefits can overcome that recurring cost, while cards with quarterly category limits were evaluated based on how much work is required to maximize the rewards.
Favorable Aspects of the Best Cash Back Credit Cards
- Several leading cash back cards earn unlimited 2% or the equivalent on broad everyday spending.
- Category cards can earn 3%, 5%, 6%, or more on qualifying household purchases.
- Most cards in this ranking charge a $0 annual fee.
- Welcome offers can provide approximately $200 to $300 or more in first-year value.
- Several cards combine cash back with 0% introductory APR financing.
- Cash rewards are generally easier to understand than airline miles or hotel points.
- Consumers can combine flat-rate and category cards to increase total household rewards.
- Some cards provide additional benefits such as cell phone protection, Disney streaming credits, purchase protections, or travel benefits.
- Cash back can generally be redeemed as statement credits or through other flexible options.
- Many rewards programs have no practical annual earning limit on ordinary purchases.
Unfavorable Aspects of Cash Back Credit Cards
- The highest cash-back rates frequently apply only to specific merchant categories.
- Quarterly or annual spending limits can restrict elevated rewards.
- Some cards require quarterly activation or category selection.
- Interest charges can quickly exceed cash-back earnings when balances are carried.
- Foreign transaction fees apply to several otherwise strong domestic cash-back cards.
- Premium cash-back cards may charge an annual fee after the first year.
- Merchant coding can prevent certain purchases from qualifying for expected bonus rewards.
- Flat-rate 1.5% cards can trail unlimited 2% competitors over the long term.
- Welcome bonuses can encourage unnecessary spending if cardholders chase the required threshold.
- Applicants generally need good to excellent credit for the strongest rewards cards.
1. Wells Fargo Active Cash® Credit Card – Best Overall Cash Back Credit Card

The Wells Fargo Active Cash® Credit Card earns the number-one position among the best cash back credit cards in 2026 because it combines one of the simplest rewards structures available with a competitive welcome offer, introductory financing, and practical consumer benefits without charging an annual fee. Cardholders earn unlimited 2% cash rewards on qualifying purchases without needing to activate quarterly categories, select preferred merchants, or monitor annual reward limits, making Active Cash particularly effective for miscellaneous spending that does not naturally fit specialized bonus categories. New cardholders can currently earn a $200 cash rewards bonus after spending $500 in purchases within the first three months and receive 0% introductory APR for 12 months from account opening on purchases and qualifying balance transfers before an 18.49%, 24.49%, or 28.49% variable APR applies. Additional benefits include up to $600 in eligible cell phone protection subject to a deductible, auto rental collision damage coverage, roadside assistance resources, Visa Signature privileges, Wells Fargo merchant offers, Zero Liability Protection, and multiple reward redemption methods, creating one of the most complete all-purpose cash-back packages available for $0 per year.
Wells Fargo Active Cash® Card Facts Table
| Feature | Details |
| Credit Card Issuer | Wells Fargo Bank, N.A. |
| Payment Network | Visa Signature |
| Rewards Type | 0% Intro APR – Customized Cash Rewards |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Rewards | Unlimited 2% cash rewards on qualifying purchases |
| Welcome Bonus | $200 cash rewards after $500 in purchases within the first 3 months |
| Intro Purchase APR | 0% introductory APR for 12 months |
| Intro Balance Transfer APR | 0% introductory APR for 12 months on qualifying balance transfers |
| Regular APR | 18.49%, 24.49%, or 28.49% Variable APR |
| Balance Transfer Fee | Greater of $5 or 3% during the introductory transfer period; afterward up to 5% with a $5 minimum |
| Foreign Transaction Fee | 3% |
| Best For | Simple unlimited flat-rate cash rewards on domestic everyday purchases |
| Notable Benefits | Cell phone protection, flexible rewards redemption, $0 annual fee, digital banking tools, fraud protection |
Why Wells Fargo Active Cash Ranks First
Wells Fargo Active Cash ranks first because an unlimited 2% return gives consumers an excellent rewards foundation without requiring them to organize their purchases around quarterly promotions or merchant categories. A household placing $30,000 of ordinary qualifying spending on Active Cash would generate approximately $600 in cash rewards before considering the $200 welcome bonus, and unlike category cards, that return does not decline simply because the spending occurs at a merchant outside a preferred category. Citi Double Cash can effectively match 2%, but Active Cash provides the full reward structure more directly while also including a purchase introductory APR and a lower spending requirement for its $200 bonus. The addition of eligible cell phone protection and Visa Signature benefits gives Active Cash enough supplemental value to rank above other simple flat-rate products.
2. Chase Freedom Unlimited® Credit Card – Best for Everyday Cash Back and Dining

The Chase Freedom Unlimited® Credit Card ranks second because it combines a strong general-purchase earning rate with several permanent elevated cash-back categories that can outperform traditional 2% cards for consumers who regularly spend at restaurants, drugstores, and through Chase Travel. Cardholders earn 5% cash back on qualifying travel purchased through Chase Travel, 3% on dining including eligible takeout and delivery services, 3% at drugstores, and unlimited 1.5% on most other qualifying purchases. New cardholders can currently earn a $200 bonus after spending $500 within the first three months and receive 0% introductory APR for 15 months on purchases and balance transfers, followed by an 18.24%–27.74% variable APR. Rewards are earned through Chase Ultimate Rewards, providing flexibility to redeem for cash, travel, gift cards, and other eligible options, and consumers with other compatible Chase products can potentially build a more advanced reward strategy. The main drawbacks are a 3% foreign transaction fee and a 1.5% general-purchase rate that trails Active Cash and Citi Double Cash, but the bonus categories compensate for that difference for many households.
Chase Freedom Unlimited® Card Facts Table
| Feature | Details |
| Card Issuer | JPMorgan Chase Bank, N.A. |
| Payment Network | Visa |
| Rewards Type | Cash Back Rewards Credit Credit |
| Recommended Credit | Good to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Rewards | Unlimited Cash Back |
| Intro Offer | $200 |
| Rewards Rate | 1.5%-5% Cashback |
| Intro APR | 0% APR for 15M on P&T |
| Regular APR | 18.24%-27.74% Variable APR |
Why Chase Freedom Unlimited Ranks Second
Chase Freedom Unlimited ranks second because its hybrid rewards structure can outperform a basic flat-rate card when a meaningful portion of household spending falls into its permanent 3% dining and drugstore categories. A consumer spending $6,000 annually at restaurants and drugstores earns approximately $180 from those transactions compared with $120 on a 2% card, while ordinary purchases still earn a respectable unlimited 1.5%. The 15-month introductory APR is also longer than Active Cash’s current 12-month promotion, and integration with Chase Ultimate Rewards gives the card more strategic value for consumers who maintain compatible Chase products. Active Cash retains first place because 2% on all ordinary purchases is simpler and stronger for general spending, but Freedom Unlimited is arguably superior for households with substantial dining and drugstore expenses.
3. Citi Double Cash® Credit Card – Best for Long-Term Flat-Rate Cash Back
The Citi Double Cash® Credit Card ranks third because it provides one of the strongest no-annual-fee flat-rate reward structures for consumers who consistently pay their purchases, effectively returning up to 2% cash back through 1% when an eligible purchase is made and another 1% as the purchase is paid. There are no rotating categories or standard annual reward caps, and qualifying hotel, rental car, and attraction reservations made through Citi Travel can earn an elevated 5% total cash-back rate. The card currently provides a $200 cash-back bonus after spending $1,500 on purchases within the first six months and includes 0% introductory APR for 18 months on qualifying balance transfers, although the promotional APR does not generally apply to purchases. After the promotional balance-transfer period, the current regular variable APR ranges from approximately 17.49% to 27.49%. Double Cash works particularly well as a permanent catch-all card for purchases that would otherwise earn only 1% on category cards, and it can be paired with other Citi ThankYou products for consumers who want additional reward flexibility.
Citi Double Cash® Card Facts Table
| Feature | Details |
| Credit Card Issuer | Citi |
| Payment Network | Mastercard |
| Rewards Type | Cash Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Standard Rewards | Up to 2% cash back |
| Rewards Structure | 1% when you buy + 1% as you pay |
| Rewards Cap | None |
| Citi Travel Rewards | Up to 5% total on eligible bookings |
| Welcome Offer | Current offer may be available |
| Foreign Transaction Fee | 3% |
| Balance Transfers | Introductory offer may be available |
| Main Redemption Options | Statement credit, direct deposit, check and other eligible options |
Why Citi Double Cash Ranks Third
Citi Double Cash ranks third because its effective 2% reward structure is exceptionally difficult to beat for miscellaneous long-term spending, especially when a consumer does not want to remember bonus categories. Active Cash ranks ahead because Wells Fargo awards its 2% structure more directly and currently combines it with purchase financing and a welcome bonus requiring considerably less spending, while Freedom Unlimited provides higher permanent category rewards. Double Cash nevertheless becomes particularly attractive for consumers who already use Citi ThankYou rewards or need an extended balance-transfer promotion. Someone spending $40,000 annually in ordinary qualifying purchases could generate approximately $800 in total cash back when purchases are paid, demonstrating why the card remains one of the strongest general-purpose options available.
4. Capital One Savor Cash Rewards Credit Card – Best for Dining, Groceries and Entertainment
The Capital One Savor Cash Rewards Credit Card ranks fourth because its unlimited 3% categories align with some of the most common discretionary and household expenses, providing elevated cash back at qualifying grocery stores, restaurants, entertainment merchants, and popular streaming services without requiring quarterly activation. The card also earns unlimited 5% cash back on eligible hotels, vacation rentals, and rental cars booked through Capital One Travel and 1% on most other purchases. New cardholders can currently earn a $200 cash bonus after spending $500 within the first three months and receive 0% introductory APR for 12 months on purchases and balance transfers before an 18.49%–28.49% variable APR applies. Savor charges no annual fee and no foreign transaction fee, giving it an international advantage over many domestic cash-back competitors, although qualifying grocery rewards exclude superstores such as Walmart and Target. For households spending heavily on dining, groceries, movies, concerts, attractions, and streaming subscriptions, Savor can generate significantly more rewards than a 2% flat-rate card.
Capital One Savor Card Facts Table
| Feature | Details |
|---|---|
| Credit Card Issuer | Capital One |
| Payment Network | Mastercard |
| Reward Type | Cash Back Credit Card |
| Recommended Credit Score | Good to Excellent Credit Score (690-850) |
| Annual Fee | $0 for the current public offer |
| Security Deposit | None |
| Standard Rewards | Unlimited 1% cash back on eligible purchases outside bonus categories |
| Bonus Rewards | 3% at eligible grocery stores and on dining, entertainment and popular streaming; 5% on eligible Capital One Travel bookings; 8% on qualifying Capital One Entertainment purchases |
| Welcome Bonus | $200 after $500 in purchases within 3 months of account opening for eligible applicants |
| Intro APR | 0% introductory APR on purchases and balance transfers for 12 months |
| Regular APR | 18.49%–28.49% variable APR after the introductory period, based on creditworthiness |
| Balance Transfer Fee | 3% on transferred amounts during the first 12 months; later promotional transfers may carry a 4% fee |
| Cash Advance Fee | 5% of the advance, with a $5 minimum |
| Foreign Transaction Fees | None |
| Credit Bureau Reporting | Account activity is generally reported to Equifax, Experian and TransUnion |
| Credit Line Increases | May be available after account review; not guaranteed |
| Best For | Food-focused households, frequent diners, entertainment buyers and streaming subscribers seeking no-annual-fee cash back |
| Employee Cards | Not applicable to this consumer card; authorized users may be added |
Why Capital One Savor Ranks Fourth
Capital One Savor ranks fourth because unlimited 3% rewards across groceries, dining, entertainment, and streaming can create exceptionally strong household value without requiring an annual membership charge. A family spending $6,000 annually at qualifying grocery stores, $4,000 at restaurants, and $2,000 on entertainment and streaming would generate approximately $360 from those categories alone, compared with $240 from a standard 2% card. Savor ranks below the first three cards because purchases outside its preferred categories normally earn only 1%, making it less effective as a one-card solution. When paired with a 2% flat-rate card, however, Savor becomes one of the most powerful no-fee category cards in the market.
5. Discover it® Cash Back Credit Card – Best for First-Year Cash Back and Rotating Categories

The Discover it® Cash Back Credit Card ranks fifth because it combines rotating 5% bonus categories with one of the most unusual introductory reward structures in the industry: Unlimited Cashback Match. Cardholders earn 5% cash back on everyday purchases in rotating quarterly categories up to the published quarterly maximum after activation and unlimited 1% on other eligible purchases. Discover automatically matches qualifying cash back earned during the first 365 days for eligible new cardmembers, meaning $400 in normal first-year rewards can become approximately $800 after the match. The card currently provides 0% introductory APR for 15 months on purchases and balance transfers, followed by a 17.49%–26.49% variable APR, and it charges neither an annual fee nor a foreign transaction fee. Discover also provides account-freeze controls, $0 fraud liability on qualifying unauthorized purchases, Social Security number monitoring, and credit-monitoring tools. The main disadvantage is that maximizing rewards requires quarterly activation and planning, while spending outside the bonus categories earns only 1% after the first-year match period ends.
Discover it® Cash Back Card Facts Table
| Feature | Details |
| Credit Card Issuer | Discover Bank |
| Payment Network | Discover |
| Reward Type | 0% APR Credit Card – Cash Back Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Rewards | 5% cash back on up to $1,500 in combined activated quarterly category purchases; 1% on other eligible purchases |
| Welcome Offer | Unlimited dollar-for-dollar Cashback Match on qualifying cash back earned during the first year for new cardholders |
| Intro Purchase APR | 0% for 15 months |
| Intro Balance Transfer APR | 0% for 15 months |
| Regular APR | 17.49%–26.49% variable |
| Intro Balance Transfer Fee | 3% of qualifying transferred balances |
| Cash Advance APR | 28.49% variable |
| Cash Advance Fee | Greater of $10 or 5% of the cash advance |
| Annual Fee | $0 |
| Foreign Transaction Fee | $0 |
| Security Deposit | None |
| Best For | Consumers who can maximize rotating 5% categories and pay attention to quarterly activations |
| Notable Benefits | Cashback Match, rotating 5% categories, introductory APR, flexible redemptions and no annual fee |
Why Discover it Cash Back Ranks Fifth
Discover it Cash Back ranks fifth because its first-year earning potential can exceed nearly every straightforward no-fee competitor when the rotating categories are maximized. A purchase receiving 5% during the first-year match period can effectively produce a total reward equal to approximately 10% once the matching cash is credited, while ordinary 1% spending effectively becomes approximately 2%. The card ranks below simpler options because the elevated categories change throughout the year, require activation, and normally have quarterly limits, which makes long-term optimization more demanding. Consumers who enjoy managing rewards may reasonably rank Discover considerably higher, while someone who wants to swipe one card without thinking about merchant categories will generally receive more consistent value from Active Cash or Double Cash.
6. Blue Cash Preferred® Credit Card from American Express – Best for U.S. Supermarkets
The Blue Cash Preferred® Credit Card from American Express ranks sixth because its 6% cash-back rate at U.S. supermarkets and on select U.S. streaming subscriptions is among the highest ongoing cash-back rates available on common household expenses. Cardholders earn 6% cash back at U.S. supermarkets on up to $6,000 in eligible purchases per year before the rate falls to 1%, unlimited 6% on select U.S. streaming subscriptions, 3% at eligible U.S. gas stations, 3% on transit including rideshare, parking, tolls, trains, and buses, and 1% on other eligible purchases. New applicants may receive a personalized offer as high as $300 cash back after spending $3,000 within the first six months. The card currently charges a $0 introductory annual fee for the first year and then $95, while also providing 0% introductory APR for 12 months on purchases and qualifying balance transfers followed by a 19.49%–28.49% variable APR. Additional value can come from an up-to-$120 annual Disney Streaming Credit after enrollment and qualifying subscription purchases.
Blue Cash Preferred® Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Cash Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 introductory annual fee for the first year, then $95 |
| Security Deposit | None |
| Standard Rewards | 1% cash back on other eligible purchases |
| Bonus Rewards | 6% at U.S. supermarkets on up to $6,000 per calendar year, then 1%; 6% on select U.S. streaming subscriptions; 3% at eligible U.S. gas stations and on transit |
| Welcome Bonus | Personalized offer as high as $300 cash back after $3,000 in purchases within six months; offers vary and some applicants may receive a lower offer or none |
| Intro APR | 0% introductory APR on purchases and eligible balance transfers for 12 months from account opening; transfers must generally be requested within the first 60 days |
| Regular APR | 19.49%–28.49% variable APR after the introductory period, based on creditworthiness and subject to change |
| Balance Transfer Fee | Either $5 or 3% of each transferred amount, whichever is greater |
| Cash Advance Fee | Either $10 or 5% of each cash advance, whichever is greater |
| Foreign Transaction Fees | 2.7% of each transaction after conversion to U.S. dollars |
| Credit Bureau Reporting | Account activity is generally reported to Equifax, Experian and TransUnion |
| Credit Line Increases | May be requested or offered after review; approval and the amount are not guaranteed |
| Best For | Households with substantial U.S. supermarket, streaming, gas and transit spending that can offset the annual fee |
| Employee Cards | Not applicable to this consumer card; Additional Card Members may be added subject to account terms |
Why Blue Cash Preferred Ranks Sixth
Blue Cash Preferred ranks sixth because few cards can match its reward potential for a household spending close to $6,000 annually at qualifying U.S. supermarkets. Maximizing the 6% grocery category produces approximately $360 in annual cash back before streaming, gas, transit, or additional rewards, which can comfortably exceed the $95 annual fee after the first year. It does not rank higher because the supermarket category is capped, the general purchase rate is only 1%, the foreign transaction fee reduces international usefulness, and many consumers prefer avoiding annual fees entirely. For a family spending substantially on groceries and streaming, however, Blue Cash Preferred can easily outperform several higher-ranked cards when evaluated strictly according to annual cash-back dollars.
7. Bank of America® Customized Cash Rewards Credit Card – Best for Customizable Cash Back
The Bank of America® Customized Cash Rewards Credit Card ranks seventh because it allows consumers to choose the spending category where they want to earn the highest cash-back rate rather than forcing every cardholder into the same reward structure. Under the current first-year offer, eligible new cardholders can earn 6% cash back in a selected category by combining the standard 3% choice-category rate with an additional first-year 3% bonus, while grocery stores and wholesale clubs earn 2% and other purchases generally earn unlimited 1%. The selected category can include gas and EV charging, online shopping including certain internet and streaming expenses, dining, travel, drugstores, or home improvement and furnishings. The 6% choice-category rate and 2% grocery and wholesale-club rate apply to the first $2,500 in combined qualifying purchases per quarter, after which the rate generally becomes 1%. New accounts can also earn a $200 online cash rewards bonus after spending $1,000 within the first 90 days and receive 0% introductory APR for 15 billing cycles on purchases and qualifying transfers.
Bank of America® Customized Cash Rewards Card Facts Table
| Feature | Details |
| Credit Card Issuer | Bank of America, N.A. |
| Payment Network | Visa Signature |
| Reward Type | Cash-Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| First-Year Choice Category | 6% Cash Back |
| Standard Choice Category After First Year | 3% Cash Back |
| Grocery Stores | 2% Cash Back |
| Wholesale Clubs | 2% Cash Back |
| Other Purchases | Unlimited 1% Cash Back |
| Quarterly Spending Limit | $2,500 combined in choice category, grocery stores and wholesale clubs |
| Welcome Bonus | $200 after $1,000 in purchases within 90 days |
| Intro Purchase APR | 0% for 15 billing cycles |
| Intro Balance Transfer APR | 0% for 15 billing cycles on qualifying transfers made within 60 days |
| Regular APR | 17.49%–27.49% Variable |
| Intro Balance Transfer Fee | 3% during first 60 days |
| Standard Balance Transfer Fee | 5% after introductory period |
| Category Changes | Once per calendar month |
| Best For | Consumers who want customizable cash-back categories |
| Notable Benefit | BofA Rewards bonuses can increase eligible cash-back earnings |
Why Bank of America Customized Cash Rewards Ranks Seventh
Bank of America Customized Cash Rewards ranks seventh because the ability to select a category makes the card adaptable as spending changes throughout the year. A homeowner can choose home improvement during a renovation, switch to travel before a vacation, and later select online shopping during holiday purchasing, subject to program rules and monthly category-change limits. The current first-year 6% structure makes the card particularly attractive for new applicants, although the combined $2,500 quarterly spending cap limits the amount receiving elevated rewards. Consumers with qualifying Bank of America relationships may also receive additional rewards through the bank’s relationship program, which can make the card considerably stronger for those customers than its base percentages suggest.
8. Blue Cash Everyday® Credit Card from American Express – Best for Online Shopping and Everyday Essentials

The Blue Cash Everyday® Card from American Express ranks eighth because it provides elevated rewards across three broad categories without charging an annual fee: U.S. supermarkets, U.S. online retail purchases, and U.S. gas stations. Cardholders earn 3% cash back in each category on up to $6,000 in eligible purchases per year per category before the respective rate falls to 1%, while other qualifying purchases earn 1%. Eligible new applicants may receive a personalized welcome offer as high as $200 cash back after spending $2,000 within the first six months, and the card currently provides 0% introductory APR for 15 months on purchases and balance transfers followed by a 19.49%–28.49% variable APR. The card also provides an up-to-$84 annual Disney Streaming Credit after enrollment and qualifying purchases. Blue Cash Everyday is particularly attractive for consumers who frequently shop online because U.S. online retail is a relatively uncommon 3% cash-back category among cards with no annual fee.
Blue Cash Everyday® Card from American Express Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Cash Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $0 |
| Rewards | 3% at U.S. supermarkets, U.S. online retail, and U.S. gas stations on up to $6,000 yearly in each category then 1%; 1% other purchases |
| Welcome Bonus | As high as $200 cash back after $2,000 in eligible purchases in 6 months; personalized offer may vary |
| Intro APR | 0% for 15 months on purchases and balance transfers requested within 60 days of account opening |
| Regular APR | 19.49%–28.49% variable after the introductory period |
| Balance Transfer Fee | Either $5 or 3% of each transfer, whichever is greater |
| Foreign Transaction Fee | 2.7% of each transaction after conversion to U.S. dollars |
| Best For | No-fee U.S. grocery, gas, online retail, and intro APR value |
| Notable Benefits | Up to $84 Disney Streaming Credit with enrollment, purchase protection, secondary rental coverage, and Amex Offers |
Why Blue Cash Everyday Ranks Eighth
Blue Cash Everyday ranks eighth because its three independent 3% categories cover a wide variety of recurring household expenses while requiring no annual membership fee. A cardholder could theoretically earn elevated rewards on thousands of dollars in supermarket, gasoline, and online purchases during the same year because each category has its own annual spending limit. It ranks lower than Savor and Blue Cash Preferred because its highest ongoing rate is 3%, but its lack of an annual fee makes it easier to justify for moderate spenders. The U.S. online retail category is especially valuable because many competing cards treat online purchases as ordinary 1% or 2% spending.
9. U.S. Bank Cash+® Visa Signature® Credit Card – Best for Selectable 5% Categories
The U.S. Bank Cash+® Visa Signature® Credit Card ranks ninth because it allows cardholders to select two 5% cash-back categories each quarter, providing significant reward potential for consumers willing to actively manage their account. Cardholders earn 5% cash back on the first $2,000 in combined eligible purchases each quarter across two chosen categories, 2% cash back in one selected everyday category such as grocery stores, restaurants, or gas and EV charging, and 1% on other qualifying purchases. The card also earns 5% cash back on eligible prepaid airfare, hotel, and car reservations booked directly through the U.S. Bank Travel Center. New cardholders can currently earn a $200 bonus after spending $1,000 in eligible purchases within the first 90 days and receive 0% introductory APR for the first 15 billing cycles on purchases and qualifying balance transfers. Cash+ provides substantially higher category upside than flat-rate cards, but consumers need to select categories regularly and monitor the quarterly spending cap to maximize value.
U.S. Bank Cash+ Visa Signature Card Facts Table
| Feature | Details |
| Credit Card Issuer | U.S. Bank National Association |
| Payment Network | Visa Signature |
| Reward Type | Cash-Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Rewards | 5% selected categories; 2% selected everyday category; 5% qualifying prepaid Travel Center bookings; 1% other eligible purchases |
| Welcome Bonus | $200 after $1,000 in eligible purchases within 90 days |
| Intro APR | 0% for 15 billing cycles on purchases and qualifying balance transfers |
| Regular APR | 17.74%–27.99% Variable |
| Balance Transfer Fee | 5% of each transfer or $5 minimum, whichever is greater |
| Foreign Transaction Fee | 3% of each foreign transaction |
| Best For | Consumers who can maximize customizable household spending categories |
| Notable Benefits | Custom 5% categories, $0 annual fee, introductory APR, Travel Center rewards and flexible redemptions |
Why U.S. Bank Cash+ Ranks Ninth
U.S. Bank Cash+ ranks ninth because its potential reward rate is excellent but requires considerably more active management than most of the cards above it. Fully using the $2,000 quarterly allowance in 5% categories can generate approximately $100 per quarter or $400 annually before considering 2% and Travel Center rewards, which is outstanding for a no-annual-fee card. The challenge is that consumers need to choose categories each quarter and ensure their spending aligns with eligible merchant classifications. A household that enjoys optimizing rewards can use Cash+ as an excellent specialized card, while someone seeking simplicity will generally receive a more predictable experience from Active Cash, Double Cash, or Quicksilver.
10. Capital One Quicksilver Cash Rewards Credit Card – Best for Simple International-Friendly Cash Back

The Capital One Quicksilver Cash Rewards Credit Card completes the Top 10 because it offers an uncomplicated rewards structure, introductory financing, a welcome bonus, no annual fee, and no foreign transaction fee. Cardholders earn unlimited 1.5% cash back on everyday purchases without needing to activate categories or monitor spending caps, while qualifying Capital One Travel and Capital One Entertainment transactions can earn elevated rewards. New cardholders can currently earn a $200 cash bonus after spending $500 in purchases within the first three months and receive 0% introductory APR for 15 months. The card is generally positioned toward applicants with excellent credit for its strongest offer, and after the promotional period the standard variable APR can range approximately from 18.49% to 28.49%. Quicksilver’s biggest weakness is straightforward: 1.5% is less than the 2% offered by Wells Fargo Active Cash or Citi Double Cash on ordinary purchases. Its lack of foreign transaction fees and easy redemption structure nevertheless make it a practical one-card option for consumers who value simplicity and international usability.
Capital One Quicksilver Cash Rewards Card Facts Table
| Quick Fact | Details |
| Credit Card Issuer | Capital One |
| Payment Network | Mastercard |
| Rewards Type | 0% Intro APR – Cash Back Rewards |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $0 annual fee |
| Rewards | Unlimited 1.5% cash back; 5% on eligible hotels, vacation rentals and rental cars through Capital One Travel |
| Welcome Bonus | $200 after $500 in purchases in 3 months |
| Intro APR | 0% on purchases and balance transfers for 15 months |
| Regular APR | 18.49%–28.49% variable |
| Balance Transfer Fee | Fee applies to promotional-rate transfers; verify current pricing disclosure |
| Foreign Transaction Fee | None |
| Best For | Low-maintenance cash back, introductory financing and foreign purchases |
| Notable Benefits | No annual or foreign transaction fee, flexible redemption and Capital One Travel rate |
Why Capital One Quicksilver Ranks Tenth
Capital One Quicksilver ranks tenth because its unlimited 1.5% return has been surpassed by 2% flat-rate competitors, but the card remains competitive when simplicity, international usability, and introductory value are considered together. A consumer spending $20,000 annually would earn approximately $300 in base cash back compared with approximately $400 on a 2% card, creating a $100 annual opportunity cost, but a traveler who would otherwise pay a 3% foreign transaction fee can quickly recover some of that difference on overseas purchases. Quicksilver is therefore best for consumers who value one predictable earning rate, Capital One’s redemption platform, a $200 introductory bonus, and no international surcharge rather than maximizing every domestic purchase.
2026 Best Cash Back Credit Cards Comparison Table
| Credit Card | Intro Offer | Rewards Rate | Annual Fee | Intro APR | Regular APR |
| Wells Fargo Active Cash® Card | $200 cash rewards bonus | Unlimited 2% | $0 | 0% for 12 months on purchases and qualifying transfers | 18.49%, 24.49%, or 28.49% Variable |
| Chase Freedom Unlimited® Card | $200 bonus | 1.5%–5% | $0 | 0% for 15 months on purchases and transfers | 18.24%–27.74% Variable |
| Citi Double Cash® Card | $200 cash back | Up to 2% everyday; 5% select Citi Travel | $0 | 0% for 18 months on qualifying balance transfers | Approximately 17.49%–27.49% Variable |
| Capital One Savor Card | $200 cash bonus | 1%–5% depending on category | $0 | 0% for 12 months on purchases and transfers | 18.49%–28.49% Variable |
| Discover it® Cash Back Card | Unlimited Cashback Match | 1%–5% | $0 | 0% for 15 months on purchases and transfers | 17.49%–26.49% Variable |
| Blue Cash Preferred® Card | Up to $300 personalized cash-back offer | 1%–6% | $0 first year, then $95 | 0% for 12 months on purchases and transfers | 19.49%–28.49% Variable |
| BofA® Customized Cash Rewards Card | $200 cash rewards bonus | 1%–6% under current first-year structure | $0 | 0% for 15 billing cycles | 17.49%–27.49% Variable |
| Blue Cash Everyday® Card from AMex | Up to $200 personalized offer | 1%–3% | $0 | 0% for 15 months on purchases and transfers | 19.49%–28.49% Variable |
| U.S. Bank Cash+ Visa Signature Card | $200 rewards bonus | 1%–5% | $0 | 0% for 15 billing cycles | Approximately 17.99%–28.24% Variable |
| Capital One Quicksilver Cash Rewards Card | $200 cash bonus | 1.5%+ | $0 | 0% for 15 months | Approximately 18.49%–28.49% Variable |
Best Cash Back Credit Card for Flat-Rate Cash Back
The Wells Fargo Active Cash Card is the strongest overall flat-rate cash-back choice in this ranking because cardholders immediately earn unlimited 2% cash rewards on qualifying purchases without category activation, spending caps, or a requirement to wait until purchases are paid before receiving the entire stated reward structure. Citi Double Cash can effectively provide the same 2% total return through its 1% when purchasing and additional 1% as purchases are paid, making it an excellent long-term alternative, while Capital One Quicksilver provides only 1.5% but adds no foreign transaction fee. Consumers who want one primary card for groceries, utilities, insurance, online shopping, travel, medical bills, and miscellaneous purchases without thinking about merchant categories will generally receive the best blend of simplicity and reward value from Active Cash.
Best Cash Back Credit Card for Dining
Capital One Savor and Chase Freedom Unlimited are the strongest dining cards in this ranking because both provide unlimited 3% cash back on eligible restaurant purchases while charging no annual fee. Savor is better suited to consumers whose lifestyle spending also includes grocery stores, entertainment, and streaming because those categories receive the same 3% rate, while Freedom Unlimited provides additional 3% rewards at drugstores and 5% through Chase Travel. Someone who spends $6,000 annually at restaurants would earn approximately $180 from either card compared with $120 using a 2% flat-rate card, creating a $60 annual advantage before considering other categories. Savor also charges no foreign transaction fee, making it the stronger dining option for consumers who frequently eat at restaurants while traveling internationally.
Best Cash Back Credit Card for Groceries
Blue Cash Preferred from American Express is the strongest grocery-focused card in the ranking because it earns 6% cash back at U.S. supermarkets on up to $6,000 in eligible annual purchases before falling to 1%, creating as much as approximately $360 of grocery cash back when the cap is fully maximized. Capital One Savor is the stronger no-annual-fee alternative because qualifying grocery-store purchases earn unlimited 3%, while Blue Cash Everyday provides another $0-fee option with 3% at U.S. supermarkets on up to $6,000 annually. Consumers should remember that merchant coding matters: warehouse clubs, superstores, and certain specialty retailers may not qualify as traditional supermarkets or grocery stores. The best grocery card therefore depends not only on annual food spending but also on where the household actually shops.
Best Cash Back Credit Card for Online Shopping
Blue Cash Everyday from American Express and Bank of America Customized Cash Rewards are especially strong for online shoppers. Blue Cash Everyday automatically earns 3% cash back on eligible U.S. online retail purchases on up to $6,000 annually before reverting to 1%, while Bank of America allows online shopping to be selected as its preferred category and currently offers an enhanced first-year reward rate under the promotional structure. The Bank of America category can also cover certain internet, cable, phone-plan, and streaming transactions, giving it broader potential value, although the combined quarterly spending cap needs to be considered. Consumers who prefer automatic rewards without selecting categories may favor Blue Cash Everyday, while shoppers whose spending changes throughout the year may appreciate Bank of America’s ability to change the preferred category.
Best Cash Back Credit Card for Rotating or Selectable 5% Categories
Discover it Cash Back and U.S. Bank Cash+ are the leading 5% category cards in the ranking but use different approaches. Discover publishes rotating quarterly categories and requires activation, while Cash+ lets cardholders choose two eligible 5% categories each quarter on up to $2,000 in combined spending. Discover can be exceptional during the first year because Cashback Match can effectively double qualifying rewards once the match is credited, while Cash+ gives cardholders greater control over which categories receive the elevated rate. Consumers who enjoy tracking promotions and adjusting spending can earn considerably more than a flat-rate card, while anyone who frequently forgets category activation or selection should generally use Active Cash or Double Cash instead.
Best Cash Back Credit Card for 0% Intro APR
Chase Freedom Unlimited, Discover it Cash Back, Blue Cash Everyday, Bank of America Customized Cash Rewards, U.S. Bank Cash+, and Capital One Quicksilver all provide introductory financing periods of approximately 15 months or billing cycles under current offers, making them especially attractive for consumers who want rewards and temporary financing in the same account. Wells Fargo Active Cash and Capital One Savor provide shorter 12-month promotional periods, while Blue Cash Preferred also currently provides 12 months. Citi Double Cash takes a different approach by emphasizing an 18-month promotional balance-transfer APR rather than purchase financing. Consumers should never choose a cash-back card solely because it advertises 0% APR; the financed balance should still be divided by the promotional months to establish a monthly payment that reaches zero before the regular variable APR begins.
Best Cash Back Credit Card for International Purchases
Capital One Savor and Capital One Quicksilver are among the strongest international cash-back options in this ranking because neither charges a foreign transaction fee and both operate on the Mastercard network, giving travelers broad international acceptance. Savor is particularly valuable for qualifying dining purchases abroad when transactions meet the applicable merchant-category requirements, while Quicksilver provides a simple 1.5% rate on general purchases. Discover it Cash Back also does not charge a foreign transaction fee, but travelers should research Discover acceptance at their destination and carry a backup Visa or Mastercard. Wells Fargo Active Cash, Chase Freedom Unlimited, Citi Double Cash, and several other strong domestic cards generally charge a foreign transaction fee, reducing their suitability for routine international spending.
Cash Back Credit Card APRs and Interest Costs
Cash back should never distract consumers from the much greater financial impact of credit card interest because regular APRs across leading rewards cards currently extend from the high teens into the upper 20% range. Consider a consumer earning 2% cash back while carrying a $5,000 balance at an APR near 25%: the $100 in rewards generated by $5,000 of purchases can be overwhelmed several times over by annual interest expense when the balance is repaid slowly. Paying the full statement balance by the due date generally preserves the value of rewards and prevents interest from converting a profitable cash-back strategy into expensive revolving debt. Introductory APR offers can temporarily reduce financing costs, but cardholders should establish a payoff schedule from the beginning instead of assuming another promotional transfer will be available later.
Can a Student Apply for a Cash Back Credit Card?
Students can apply for mainstream cash-back credit cards when they meet the issuer’s age, income, identity, and underwriting requirements, but many products in this Top 10 ranking generally target applicants with established good-to-excellent credit. Students with limited credit history may receive better approval odds through dedicated student cash-back products that offer similar reward structures with underwriting designed around thinner credit files. Applicants under age 21 can also face additional income requirements under federal credit card regulations. The strongest strategy for a new student cardholder is generally to place a few normal budgeted expenses on the account, pay every statement on time, avoid carrying unnecessary balances, and allow responsible credit history to develop before applying for increasingly premium rewards products.
What Credit Score Is Needed for the Best Cash Back Credit Cards?
Most of the leading cash-back cards in this ranking generally target consumers with good or excellent credit profiles, often broadly corresponding to FICO scores beginning around the upper 600s and extending through the 700s and 800s, although no particular score guarantees approval. Issuers can evaluate income, housing costs, payment history, total debt, credit utilization, recent applications, account age, existing banking relationships, and internal risk models in addition to any credit score. Capital One Quicksilver’s strongest standard offer can be particularly oriented toward excellent-credit applicants, while Discover, Chase, Wells Fargo, American Express, Bank of America, Citi, and U.S. Bank each apply their own underwriting standards. Consumers should use available prequalification tools when appropriate and avoid applying simply because an advertised recommended score range appears to match their current score.
Should You Carry a Balance to Earn More Cash Back?
Consumers generally should not carry a balance merely to earn cash-back rewards because paying interest provides no additional reward and can dramatically reduce or completely eliminate the financial value of the card. A $1,000 purchase earning 2% produces only $20 in cash back, while carrying that same $1,000 for a year at a high variable APR can cost well over $200 in interest depending on the rate and payment schedule. Credit scores also do not require consumers to pay interest, so cardholders can build positive payment history while paying statements in full. The best cash-back strategy is to earn rewards on purchases that would have been made anyway and then pay those purchases using money already available in the household budget.
Cash Back Credit Cards vs. Travel Rewards Credit Cards
Cash-back cards provide predictable value and easy redemptions, while travel rewards cards can potentially generate higher value for consumers who are willing to transfer points, search award inventory, use travel portals, or maximize airline and hotel programs. A dollar of cash back is always worth a dollar toward whatever financial priority matters most, while the value of 10,000 airline miles or hotel points depends on the program and redemption. Consumers who rarely travel, dislike complex rewards systems, or prefer reducing monthly expenses may receive more practical value from cash back. Frequent travelers capable of obtaining premium award redemptions can potentially exceed the effective return available from cash-back cards, making the correct choice dependent on lifestyle rather than one reward type being universally better.
How to Choose the Best Cash Back Credit Card
Choosing the best cash-back card starts with reviewing several months of actual spending rather than selecting whichever card advertises the highest percentage. Consumers spending heavily across many unrelated categories may benefit most from an unlimited 2% card such as Active Cash or Double Cash, while households spending heavily on groceries and restaurants may earn more with Savor or Blue Cash Preferred. Online shoppers should evaluate Blue Cash Everyday or Customized Cash Rewards, reward optimizers can consider Discover it Cash Back or U.S. Bank Cash+, and international travelers should place additional weight on foreign transaction fees. Annual fees, welcome bonuses, introductory APRs, category limits, credit requirements, redemption methods, and long-term usefulness should then be compared to determine which product provides the highest realistic net annual value.
Can You Have Multiple Cash Back Credit Cards?
Consumers can maintain multiple cash-back credit cards and may significantly improve overall rewards by assigning different cards to different spending categories. One common strategy is to use Wells Fargo Active Cash or Citi Double Cash for purchases that do not receive elevated rewards elsewhere, Capital One Savor for dining and groceries, Blue Cash Everyday for U.S. online retail, and Discover or U.S. Bank Cash+ when a 5% category applies. The disadvantage is increased account complexity because multiple cards create additional due dates, statements, spending limits, and potential annual fees to manage. Consumers should only add another cash-back card when its additional rewards or benefits meaningfully exceed the administrative burden and potential credit impact of opening a new account.
Are Authorized User Cash Back Credit Cards Worth It?
Adding an authorized user to a cash-back account can increase household reward earnings when the additional cardholder uses the account for ordinary budgeted expenses, but the primary account holder remains legally responsible for repayment of authorized transactions. Families using one card for groceries, restaurants, gasoline, or household bills can consolidate rewards more quickly when multiple people use authorized-user cards, particularly when the rewards program does not charge an additional-user fee. However, category caps apply across the account rather than separately to each authorized user in most cases, meaning additional spending can cause a quarterly or annual reward limit to be reached sooner. Authorized users should therefore be trusted completely, and spending expectations should be established before additional cards are distributed.
Final Verdict: Best Cash Back Credit Cards in 2026
The Wells Fargo Active Cash® Card is our Best Rated Cash Back Credit Card in 2026 because unlimited 2% cash rewards, a $200 introductory bonus, a $0 annual fee, 12 months of introductory financing, eligible cell phone protection, Visa Signature privileges, rental car coverage, merchant offers, and flexible rewards redemption create one of the most complete and easiest-to-use packages available. Chase Freedom Unlimited® ranks second because its combination of 1.5% base cash back, 3% dining and drugstores, 5% Chase Travel, a $200 welcome bonus, and a 15-month introductory APR gives it outstanding versatility, while Citi Double Cash® ranks third for consumers who want an effective unlimited 2% structure and strong long-term simplicity. Capital One Savor is the best option for many dining, grocery, entertainment, and streaming households, Discover it Cash Back delivers exceptional first-year potential through Cashback Match and rotating 5% categories, and Blue Cash Preferred is particularly strong for families maximizing U.S. supermarket spending. Bank of America Customized Cash Rewards, Blue Cash Everyday, U.S. Bank Cash+, and Capital One Quicksilver each serve valuable specialized roles for customizable categories, online shopping, selectable 5% rewards, and international-friendly simplicity. Ultimately, the best cash-back card is the account that aligns with real household spending while charging manageable fees and encouraging responsible repayment, because consistently earning 2%, 3%, 5%, or 6% on purchases already included in a budget can produce hundreds of dollars in annual value, while carrying high-interest balances can erase those rewards many times over.