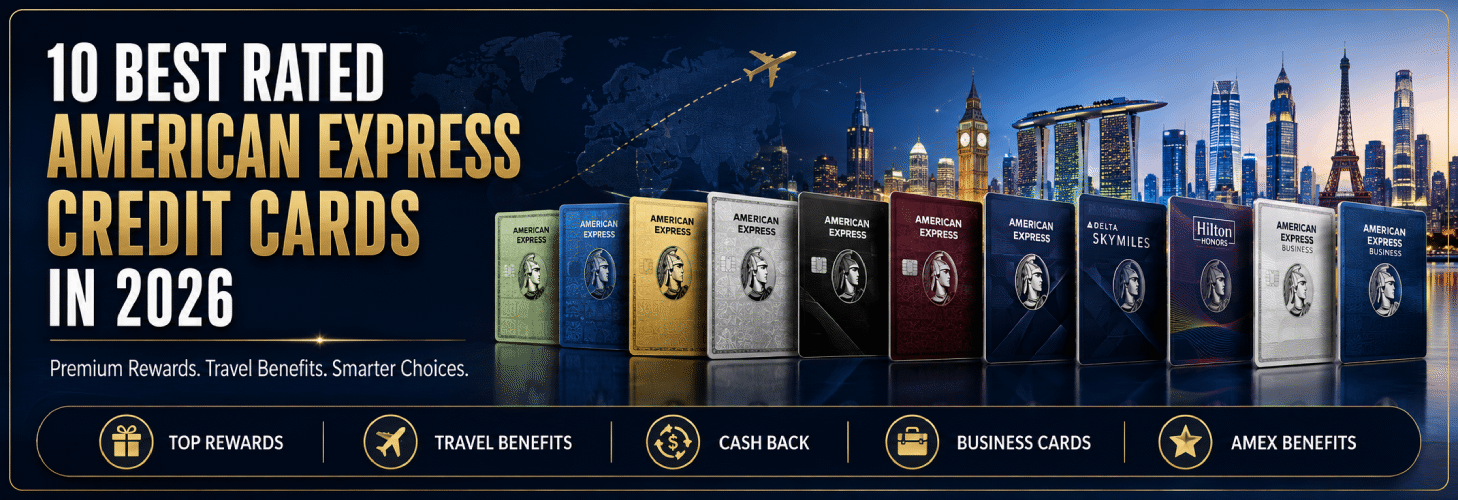
10 Best Rated American Express Credit Cards in 2026
American Express has one of the most varied credit card portfolios in the United States, ranging from no-annual-fee cash-back cards to premium travel cards, hotel and airline products, and business cards that earn flexible Membership Rewards points. The best American Express card is not automatically the one with the largest welcome offer or highest annual fee. It is the card whose reward categories, credits, travel privileges, redemption options, and yearly price match the way a household or business already spends. This editorial guide ranks ten of the best-rated American Express credit cards for 2026, compares their current prices and headline terms, and explains where each product delivers the strongest practical value. The list includes cards issued by American Express National Bank as well as co-branded products offered with Hilton, Marriott Bonvoy, and Delta Air Lines. Every card name in the comparison table and every official website entry in the Quick Facts tables links directly to the relevant company product page so readers can confirm the latest offer before applying.
Important Note About American Express Credit Card Offers, APRs and Eligibility
Card details in this article were reviewed on August 18, 2026, and can change without notice. American Express increasingly displays personalized welcome offers and account-specific APRs during the application process, so a publicly advertised maximum bonus is not a promise that every applicant will receive it. Enrollment may be required for statement credits, benefits can have monthly, quarterly, semiannual, or calendar-year limits, and merchant coding determines whether a purchase earns a bonus rate. Approval is never guaranteed, even for someone with a strong credit score, because the issuer can consider income, debt, payment history, recent applications, and its existing relationship with the applicant. A prospective cardholder should read the official rates-and-fees disclosure and benefit terms shown with the application, avoid spending only to earn a bonus, and pay the statement balance in full whenever possible. This article is independent editorial information rather than individualized financial, legal, tax, or credit advice.
What Are the Best Rated American Express Credit Cards in 2026?
The American Express® Gold Card ranks first overall because its rich restaurant and U.S. supermarket rewards can fit a broad rewards-focused household, while the Blue Cash Preferred® Card from American Express is the leading cash-back choice and The Platinum Card® from American Express is the strongest premium-travel selection. The Blue Cash Everyday® Card from American Express is the most approachable no-annual-fee option and the best balance-transfer card in this specific Amex lineup. The American Express® Green Card offers a lower-cost path to transferable travel points, and the Hilton Honors American Express Aspire Card, Marriott Bonvoy Brilliant® American Express® Card, and Delta SkyMiles® Reserve American Express Card serve loyal travelers who can repeatedly use brand-specific benefits. The Blue Business® Plus Credit Card from American Express and American Express® Business Gold Card round out the ranking with compelling options for eligible small-business owners. These rankings reward durable annual value, not merely a temporary welcome bonus.
How We Rated the Best American Express Credit Cards
Each card was evaluated on its net value after the annual fee, usefulness of reward categories, redemption flexibility, welcome-offer accessibility, travel and purchase protections, statement-credit usability, foreign transaction fees, intro APR availability, and fit for a clearly defined customer. Flexible Membership Rewards points received extra credit when they could transfer to travel partners, while cash-back cards were judged on transparent everyday returns and financing value. Co-branded products were assessed according to how well their elite status, free-night awards, lounge privileges, baggage benefits, or airline credits could offset their price for a realistic loyalist. We also penalized complicated credits, narrow merchant restrictions, category caps, weak non-bonus earnings, and benefits that require substantial incremental spending. Editorial ratings are comparative opinions on a five-point scale; they do not represent American Express ratings, approval odds, or a prediction of investment-like returns.
Favorable Details About American Express Credit Cards
- Wide product range: American Express offers cash back, transferable points, airline miles, hotel points, no-annual-fee cards, premium products, and business options within one ecosystem.
- Strong everyday categories: Several cards reward restaurants, U.S. supermarkets, U.S. gas stations, transit, streaming services, online retail, travel, or business expenses at elevated rates.
- Valuable travel partners: Membership Rewards points can transfer to participating airline and hotel loyalty programs, which can unlock more flexibility than fixed-value statement credits.
- Useful premium benefits: Depending on the card, benefits may include airport lounge access, annual free-night awards, hotel status, airline baggage privileges, travel protections, and application-fee credits.
- Preapproval-friendly process: American Express may let an applicant learn whether the application is approved without an initial effect on the credit score; accepting the card can still affect the score.
- No foreign transaction fee choices: Most travel-oriented cards in this ranking do not charge a foreign transaction fee, making them more suitable for purchases abroad.
- Consumer and business options: Owners of eligible businesses can earn rewards on business expenses while separating company purchases from personal spending.
Unfavorable Details About American Express Credit Cards
- High annual fees: Premium personal and co-branded cards in this list cost from $325 to $895 per year, and the fee is due whether or not every benefit is used.
- Credit complexity: Many statement credits are divided by month, quarter, or half-year and require enrollment or purchases with specific merchants.
- Acceptance limitations: American Express acceptance is broad but not universal, especially at some smaller merchants and in certain international destinations, so travelers may need a Visa or Mastercard backup.
- Bonus restrictions: Welcome-offer eligibility can depend on application history, past ownership of related cards, and the offer language presented to the applicant.
- Category caps: Several headline earning rates drop after a yearly spending threshold, which can reduce value for very high spenders.
- Weak borrowing value on premium cards: Most premium and co-branded cards do not provide a 0% intro APR, and variable Pay Over Time or purchase APRs can make carried balances costly.
- Co-branded inflexibility: Hilton, Marriott, and Delta rewards are most valuable to customers who consistently use the associated travel brand.
1. American Express® Gold Credit Card

The American Express® Gold Credit Card earns the top position because it combines transferable rewards with categories that many households use every week. It earns 4X Membership Rewards points at restaurants worldwide on up to $50,000 per calendar year and 4X at U.S. supermarkets on up to $25,000 per calendar year, with 1X after each cap. It also earns 5X on prepaid hotels booked through AmexTravel.com or the Amex Travel App, 3X on flights booked directly with airlines or through Amex Travel, 2X on eligible prepaid car rentals and cruises booked through Amex Travel, and 1X elsewhere. The $325 annual fee is significant, but up to $120 in annual dining credits, $120 in Uber Cash, $100 in Resy credits, and $84 in Dunkin’ credits can reduce the effective cost for cardholders who naturally use the participating services and enroll where required. Membership Rewards transfers, The Hotel Collection benefits, no foreign transaction fees, and selected travel and purchase protections further improve the package. The tradeoffs are that the card has no included airport lounge membership, the credits are fragmented, and paying interest can quickly erase reward value.
American Express® Gold Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Cash Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $325 |
| Rewards | 5X eligible prepaid hotels; 4X restaurants worldwide and U.S. supermarkets subject to caps; 3X eligible flights; 2X eligible prepaid car rentals and cruises; 1X other purchases |
| Welcome Bonus | Personalized offer; confirm the points, spending requirement, and deadline before acceptance |
| Intro APR | None |
| Regular APR | Variable Pay Over Time APR shown in the application disclosure |
| Balance Transfer Fee | Balance transfers are generally not offered; verify application terms |
| Foreign Transaction Fee | None |
| Best For | Food-focused households that value transferable travel points |
| Notable Benefits | Dining, Uber Cash, Resy, and Dunkin’ credits; transfer partners; selected travel protections; no foreign transaction fee |
Why the American Express® Gold Card Ranks First
The Gold Card wins on the breadth and frequency of its strongest categories. Restaurant and supermarket purchases are recurring expenses rather than occasional luxury transactions, so the 4X rates can create meaningful rewards without shifting a household budget toward unfamiliar merchants. A cardholder who spends $500 per month at qualifying U.S. supermarkets and $400 per month at restaurants could earn 43,200 Membership Rewards points a year from those categories before counting travel or other spending. That arithmetic does not make the annual fee disappear, however; the card is most convincing when the user also redeems credits at close to face value and pays the statement in full. It ranks above Platinum because its core earnings can justify ownership without frequent premium travel, and above Blue Cash Preferred because transferable points offer more redemption upside to travelers who know how to use partners.
2. Blue Cash Preferred® Credit Card from American Express
The Blue Cash Preferred® Credit Card from American Express in this ranking for straightforward cash back. It earns 6% cash back at U.S. supermarkets on up to $6,000 per year, then 1%; 6% on select U.S. streaming subscriptions; 3% at U.S. gas stations; 3% on transit such as taxis, rideshare, parking, tolls, trains, and buses; and 1% on other eligible purchases. Cash back is received as Reward Dollars that can be redeemed for statement credits, which removes the need to study transfer partners or award charts. Its $0 introductory annual fee for the first year and $95 fee thereafter are comparatively modest, and an up-to-$120 annual Disney Streaming Credit can help regular subscribers. The card also pairs rewards with 0% intro APR for 12 months on purchases and balance transfers requested within the eligible opening window. Its limitations are the $6,000 supermarket cap, a 2.7% foreign transaction fee, and the fact that cash back lacks the potential travel upside of transferable points.
Blue Cash Preferred® Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Cash Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 introductory annual fee for the first year, then $95 |
| Security Deposit | None |
| Standard Rewards | 1% cash back on other eligible purchases |
| Bonus Rewards | 6% at U.S. supermarkets on up to $6,000 per calendar year, then 1%; 6% on select U.S. streaming subscriptions; 3% at eligible U.S. gas stations and on transit |
| Welcome Bonus | Personalized offer as high as $300 cash back after $3,000 in purchases within six months; offers vary and some applicants may receive a lower offer or none |
| Intro APR | 0% introductory APR on purchases and eligible balance transfers for 12 months from account opening; transfers must generally be requested within the first 60 days |
| Regular APR | 19.49%–28.49% variable APR after the introductory period, based on creditworthiness and subject to change |
| Balance Transfer Fee | Either $5 or 3% of each transferred amount, whichever is greater |
| Cash Advance Fee | Either $10 or 5% of each cash advance, whichever is greater |
| Foreign Transaction Fees | 2.7% of each transaction after conversion to U.S. dollars |
| Credit Bureau Reporting | Account activity is generally reported to Equifax, Experian and TransUnion |
| Credit Line Increases | May be requested or offered after review; approval and the amount are not guaranteed |
| Best For | Households with substantial U.S. supermarket, streaming, gas and transit spending that can offset the annual fee |
| Employee Cards | Not applicable to this consumer card; Additional Card Members may be added subject to account terms |
Why the Blue Cash Preferred® Card Ranks Second
Blue Cash Preferred ranks second because its value is easy to understand and its reward categories cover a useful cross-section of a typical U.S. budget. Spending $6,000 per year at qualifying U.S. supermarkets generates $360 in cash back before the annual fee and before streaming, transit, or gas rewards, while a no-fee 3% grocery card would generate $180 on the same purchases. That $180 difference exceeds the ongoing $95 annual fee, although the comparison changes for households with lower supermarket spending or stores that do not code as U.S. supermarkets. The intro APR adds genuine short-term value for a planned purchase or eligible transferred debt, provided the balance is fully repaid before the promotional period ends. The card misses first place because its supermarket rate is capped, it charges for foreign transactions, and it does not earn transferable Membership Rewards points.
3. The Platinum Credit Card® from American Express

The American Express® Platinum Credit Card is the premium travel flagship in this lineup. It earns 5X Membership Rewards points on flights booked directly with airlines or through Amex Travel, on up to $500,000 in eligible flight purchases per calendar year, 5X on prepaid hotels booked through Amex Travel, and 1X on most other purchases. Its real appeal is the benefit portfolio: access to the American Express Global Lounge Collection, including Centurion Lounges and participating Priority Pass lounges after enrollment; limited Delta Sky Club visits when flying Delta under the applicable rules; up to $600 in annual hotel credits divided semiannually for eligible prepaid Fine Hotels + Resorts or The Hotel Collection bookings; and a long menu of travel, lifestyle, and entertainment credits. The 2026 annual fee is $895, which demands deliberate use. Some credits are merchant-specific, enrollment-based, or distributed by month or half-year, and the card is a poor everyday earner outside airfare and prepaid Amex Travel hotels. It is exceptional for a frequent traveler who values lounge access and premium services, but expensive clutter for someone who travels only occasionally.
The Platinum Card® from American Express Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Travel Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual fee | $895 for the basic card |
| Additional cards | $195 per Additional Platinum Card; no annual fee for Companion Platinum Cards, with different benefit access |
| Welcome offer | Personalized offer as high as 175,000 Membership Rewards points after $12,000 in eligible purchases within the first 6 months; offers vary and some applicants may be ineligible |
| Flight rewards | 5 points per dollar on eligible flights booked directly with airlines or through American Express Travel, on up to $500,000 in these purchases per calendar year |
| Hotel rewards | 5 points per dollar on eligible prepaid hotels booked through American Express Travel |
| Other rewards | 1 point per dollar on most other eligible purchases |
| Introductory APR | None advertised |
| Pay Over Time APR | 19.49% to 28.49% variable on eligible charges under current public terms; the applicant’s disclosure controls |
| Balance transfers | Not offered as a standard feature |
| Foreign transaction fee | None |
| Spending limit | No preset spending limit; purchasing power adapts and is not unlimited |
| Security deposit | None |
| Recommended credit profile | Generally good to excellent credit, with approval based on the full application and issuer underwriting |
| Rewards currency | American Express Membership Rewards points |
| Best suited for | Frequent travelers and benefit optimizers who can justify the annual fee through organic use |
Why The Platinum Card® from American Express Ranks Third
Platinum ranks third because its benefit ceiling is extraordinarily high but its cost and complexity narrow the ideal audience. A frequent traveler who would independently pay for lounge memberships, premium hotel bookings, CLEAR+, rideshare, and covered subscriptions may recover more than the annual fee. The same calculation fails when credits encourage new spending, go unused before their deadline, or replace a less expensive service with a premium one. Its 1X base rate also means it should usually be paired with another Membership Rewards card for ordinary purchases. Platinum outranks the remaining travel cards because its points are flexible and its lounge network is not tied to a single hotel or airline, but Gold and Blue Cash Preferred rank higher overall because they create value more consistently from routine expenses at substantially lower prices.
4. Blue Cash Everyday® Credit Card from American Express

The Blue Cash Everyday® Card from American Express is the best no-annual-fee personal card in this list and a practical entry point to American Express. It earns 3% cash back at U.S. supermarkets, on U.S. online retail purchases, and at U.S. gas stations, with each category capped at $6,000 in eligible purchases per calendar year before falling to 1%; other purchases earn 1%. It also offers 0% intro APR for 15 months on purchases and eligible balance transfers requested within 60 days, followed by a variable APR, making it more useful for a planned payoff strategy than the premium cards. The up-to-$84 yearly Disney Streaming Credit can add value after enrollment. The card has no annual fee, but it charges a 2.7% foreign transaction fee and does not reward dining, travel, or uncategorized spending especially well. It is best for a cost-conscious U.S. household that wants common bonus categories without keeping track of an annual break-even point.
Blue Cash Everyday® Card from American Express Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Cash Back Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $0 |
| Rewards | 3% at U.S. supermarkets, U.S. online retail, and U.S. gas stations on up to $6,000 yearly in each category then 1%; 1% other purchases |
| Welcome Bonus | As high as $200 cash back after $2,000 in eligible purchases in 6 months; personalized offer may vary |
| Intro APR | 0% for 15 months on purchases and balance transfers requested within 60 days of account opening |
| Regular APR | 19.49%–28.49% variable after the introductory period |
| Balance Transfer Fee | Either $5 or 3% of each transfer, whichever is greater |
| Foreign Transaction Fee | 2.7% of each transaction after conversion to U.S. dollars |
| Best For | No-fee U.S. grocery, gas, online retail, and intro APR value |
| Notable Benefits | Up to $84 Disney Streaming Credit with enrollment, purchase protection, secondary rental coverage, and Amex Offers |
Why the Blue Cash Everyday® Card Ranks Fourth
Blue Cash Everyday places fourth because it combines a permanent $0 annual fee with categories that are both broad and easy to use. The 3% online retail category is particularly distinctive because it can cover eligible purchases across many U.S. websites rather than one store. Its 15-month introductory APR period is also the longest in this ranking, giving it a second purpose beyond rewards. It trails Blue Cash Preferred for households that can maximize the latter card’s 6% supermarket and streaming returns, and it lacks the transferable-point potential of Gold or Platinum. Nevertheless, its low carrying cost makes it a strong long-term account, and the absence of an annual fee means the cardholder does not need to manufacture spending merely to justify keeping it.
5. American Express® Green Credit Card

The American Express® Green Credit Card is a flexible mid-tier travel card for people who want Membership Rewards without paying Gold or Platinum pricing. It earns 3X points on a broad definition of travel, 3X on transit, 3X at restaurants worldwide, and 1X on other eligible purchases. That combination can cover flights, hotels, rideshare, taxis, tolls, parking, trains, cruises, and dining more naturally than a portal-heavy travel card, although eligibility still depends on merchant coding and current terms. The $150 annual fee is easier to absorb than premium-card pricing, and up to $209 per calendar year in CLEAR+ statement credits can offset it for a traveler who would buy the service anyway. It has no foreign transaction fee and points can access Membership Rewards transfer partners. However, it does not include a comprehensive lounge membership, its base rate is only 1X, and CLEAR+ alone may not appeal to travelers who rarely use participating airports.
American Express® Green Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Travel Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $150 |
| Rewards | 3X travel, transit, and restaurants worldwide; 1X other eligible purchases |
| Welcome Bonus | Personalized offer; verify the application terms before acceptance |
| Intro APR | None |
| Regular APR | Variable Pay Over Time APR shown in the application disclosure |
| Balance Transfer Fee | Balance transfers are generally not offered; verify application terms |
| Foreign Transaction Fee | None |
| Best For | Broad travel and transit spending at a moderate annual fee |
| Notable Benefits | Up to $209 CLEAR+ credit, Membership Rewards transfer partners, travel assistance, and no foreign transaction fee |
Why the American Express® Green Card Ranks Fifth
Green ranks fifth because it occupies a useful middle ground: the card is simpler and cheaper than Platinum while rewarding more kinds of travel and transit than Gold. Its 3X travel category can be attractive to travelers who book directly with hotels, use public transportation, pay tolls, or purchase trips outside Amex Travel. A user who values flexible points but cannot use Gold’s dining credits or Platinum’s lifestyle bundle may find Green the cleaner proposition. It remains below the no-fee Blue Cash Everyday because a $150 fee requires a clear plan, and below Gold because the Green Card lacks an equally strong grocery category. CLEAR+ can make the fee math favorable, but only when the cardholder genuinely values and uses that service.
6. Hilton Honors American Express Surpass® Credit Card

The Hilton Honors American Express Surpass® Credit Card is the strongest hotel card in the ranking for committed Hilton guests. It earns 14X Hilton Honors points on eligible purchases made directly with hotels and resorts in the Hilton portfolio, 7X on eligible flights, select car rentals, and U.S. restaurants, and 3X on other purchases. The $550 annual fee buys complimentary Hilton Honors Diamond status, an annual Free Night Reward in the first year and at renewal, up to $400 in Hilton Resort Credits divided semiannually, up to $200 in flight credits divided quarterly, up to $219 in CLEAR+ credits, and selected travel protections. Additional Free Night Rewards can be earned after specified calendar-year spending thresholds. This is a concentrated value proposition: a Hilton loyalist can potentially offset the fee with the annual certificate and resort credit, while an infrequent Hilton guest may struggle to use benefits without changing travel plans. Hilton points also do not have the same cross-program flexibility as Membership Rewards points.
Hilton Honors American Express Surpass® Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Hotel Rewards – Travel Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $550 |
| Rewards | 14X eligible Hilton purchases; 7X eligible flights, select car rentals, and U.S. restaurants; 3X other purchases |
| Welcome Bonus | Current Hilton Honors points offer varies; verify the application before acceptance |
| Intro APR | None |
| Regular APR | Variable APR shown in the application disclosure |
| Balance Transfer Fee | Balance transfers are generally not offered; verify application terms |
| Foreign Transaction Fee | None |
| Best For | Frequent Hilton guests who can use resort credits, status, and free-night awards |
| Notable Benefits | Hilton Diamond status, annual Free Night Reward, up to $400 resort credit, up to $200 flight credit, and up to $219 CLEAR+ credit |
Why the Hilton Honors American Express Aspire Card Ranks Sixth
Aspire ranks sixth because it may deliver the best brand-specific hotel value on the list, yet that value is conditional on staying with Hilton. Diamond status can improve eligible stays through bonus points, potential upgrades, and property-level privileges, while the annual Free Night Reward can be worth a substantial portion of the fee when redeemed thoughtfully. The resort and flight credits can push the net value higher, but their timing and eligible-purchase rules require organization. Aspire outranks the Marriott and Delta cards because its automatic top-tier Hilton status and first-year-and-renewal free-night structure are unusually complete. It remains below the flexible Membership Rewards and cash-back cards because hotel points and Hilton-specific benefits are less useful to travelers who choose accommodations primarily by price or destination.
7. Marriott Bonvoy Brilliant® American Express® Credit Card

The Marriott Bonvoy Brilliant® American Express® Credit Card is built for travelers who spend meaningful time within the Marriott ecosystem and value automatic elite status. It earns 6X Marriott Bonvoy points on eligible purchases at participating hotels, 3X at restaurants worldwide and on flights booked directly with airlines, and 2X on other eligible purchases. Its $650 annual fee is partly countered by up to $300 in restaurant statement credits, distributed as up to $25 per month, and an annual Free Night Award after renewal worth up to 85,000 Marriott Bonvoy points under current terms. Cardholders also receive complimentary Marriott Bonvoy Platinum Elite status, 25 Elite Night Credits each calendar year, Priority Pass lounge access after enrollment, and a Global Entry or TSA PreCheck application-fee credit at the stated interval. The card can be powerful for Marriott loyalists, but the monthly dining-credit format, premium fee, and Marriott-specific currency make it a poor casual choice. Award availability, resort fees, and point requirements can also affect certificate value.
Marriott Bonvoy Brilliant® American Express® Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Hotel Rewards – Travel Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $650 |
| Rewards | 6X participating Marriott hotels; 3X restaurants worldwide and flights booked directly with airlines; 2X other purchases |
| Welcome Bonus | Current Marriott Bonvoy points offer varies; verify the application before acceptance |
| Intro APR | None |
| Regular APR | Variable APR shown in the application disclosure |
| Balance Transfer Fee | Balance transfers are generally not offered; verify application terms |
| Foreign Transaction Fee | None |
| Best For | Frequent Marriott guests seeking Platinum Elite status and a premium free-night award |
| Notable Benefits | Up to $300 dining credit, annual award up to 85,000 points, Platinum Elite status, 25 Elite Night Credits, and Priority Pass |
Why the Marriott Bonvoy Brilliant® American Express® Card Ranks Seventh
Brilliant ranks seventh because its annual Free Night Award and Platinum Elite status can be very valuable but are meaningful primarily inside Marriott Bonvoy. A traveler who redeems the certificate at an expensive participating property and uses the monthly dining credit can create a defensible case for the $650 fee before considering status and lounge access. Someone who misses several monthly credits or cannot find a desirable eligible award night will see a much weaker result. The card ranks behind Aspire because Hilton’s product offers top-tier status and a more layered set of recurring travel credits, although Marriott’s larger footprint and 85,000-point certificate may be preferable for a particular itinerary. It also ranks below flexible-point cards because transferring Marriott points to airline partners is usually less direct and less efficient than transferring Membership Rewards.
8. Delta SkyMiles® Gold American Express Credit Card

The Delta SkyMiles® Gold American Express Credit Card is the most premium Delta-focused consumer card and should be judged as an airline benefits package rather than an everyday points machine. It earns 3X miles on eligible purchases made directly with Delta and 1X on other purchases. Its $650 annual fee supports 15 Delta Sky Club visits per Medallion year under current rules, with unlimited visits available after meeting the specified annual spending threshold, four one-time guest passes, and access to Centurion Lounges when flying Delta and satisfying the applicable ticket-purchase conditions. Cardholders can also receive an annual companion certificate after renewal for eligible routes and cabins, a first checked bag free on qualifying Delta itineraries, priority boarding, TakeOff 15 on eligible award travel, a $2,500 Medallion Qualification Dollar Headstart, and qualifying Resy, rideshare, and Delta Stays credits. The card’s 1X return outside Delta is weak, and customers who do not fly Delta often enough should avoid paying for benefits they cannot use.
Delta SkyMiles® Gold American Express Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Rewards Type | Airline Rewards – Travel Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $650 |
| Rewards | 3X miles on eligible Delta purchases; 1X other eligible purchases |
| Welcome Bonus | Current Delta SkyMiles offer varies; verify the application before acceptance |
| Intro APR | None |
| Regular APR | Variable APR shown in the application disclosure |
| Balance Transfer Fee | Balance transfers are generally not offered; verify application terms |
| Foreign Transaction Fee | None |
| Best For | Frequent Delta flyers who value lounge access, a companion certificate, and status progress |
| Notable Benefits | 15 Sky Club visits under current rules, four guest passes, companion certificate, MQD Headstart, checked-bag benefit, Resy, rideshare, and Delta Stays credits |
Why the Delta SkyMiles® Reserve American Express Card Ranks Eighth
Delta Reserve ranks eighth because it can solve several expensive travel needs for a frequent Delta customer, but its rewards on general purchases are too low for broad appeal. The renewal companion certificate can potentially offset much of the annual fee on an eligible higher-priced itinerary, and Sky Club visits may be valuable to a traveler who passes through Delta hubs repeatedly. Status-oriented flyers can also use the MQD benefits strategically. Those advantages diminish quickly for someone who flies whichever airline has the lowest fare, cannot use the certificate within its rules, or already receives lounge access another way. The card belongs in a targeted wallet alongside a better everyday earner; it is not the strongest single-card solution for most consumers.
9. Blue Business® Plus Credit Card from American Express

The Blue Business® Plus Credit Card from American Express is one of the simplest ways for an eligible small business to earn Membership Rewards without an annual fee. It earns 2X points on the first $50,000 in eligible purchases each calendar year, then 1X, while eligible purchases booked through AmexTravel.com also earn 2X under current terms. The flat bonus rate reduces the need to track merchant categories, making the card useful for inventory, professional services, utilities, software, and other expenses that might not trigger a specialized bonus. A 0% introductory APR on purchases for 12 months can help finance a planned business expense, although every balance should be supported by a disciplined payoff schedule. Employee cards, expense-management tools, and Expanded Buying Power can be useful operationally. The main drawbacks are the $50,000 2X cap, a 2.7% foreign transaction fee, and the absence of premium travel benefits. Because it is a business card, applicants need a legitimate business activity and must understand the personal-liability and reporting terms in the application.
Blue Business® Plus Card from American Express Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Travel Rewards Credit Card |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee or Price | $0 |
| Rewards | 2X on the first $50,000 in eligible purchases per calendar year then 1X; eligible AmexTravel.com purchases can earn 2X under current terms |
| Welcome Bonus | 15,000 Membership Rewards points after $3,000 in eligible purchases in the first 3 months |
| Intro APR | 0% on purchases for 12 months from account opening |
| Regular APR | 17.99%–25.99% variable after the introductory period |
| Balance Transfer Fee | Balance transfers are generally not offered; verify application terms |
| Foreign Transaction Fee | 2.7% of each transaction after conversion to U.S. dollars |
| Best For | Small businesses with varied expenses up to the annual 2X cap |
| Notable Benefits | No annual fee, Membership Rewards transfers, employee cards, expense tools, and Expanded Buying Power |
Why the Blue Business® Plus Credit Card Ranks Ninth
Blue Business Plus ranks ninth overall but first among the no-fee business choices in this particular list. Its strength is efficient simplicity: an eligible business can earn 2X flexible points on many purchases that would otherwise earn only 1X, and keeping the card costs nothing in annual fees. It pairs particularly well with Business Gold, which can handle selected high-spend categories while Blue Business Plus covers miscellaneous expenses. The $50,000 annual cap makes it less rewarding for larger companies, and the foreign transaction fee makes it unsuitable for international supplier purchases. Its position also reflects audience size rather than product quality; a business card cannot be recommended as a personal spending substitute, but it can be excellent for a qualifying owner whose expenses fit the cap.
10. American Express® Business Gold Credit Card

The American Express® Business Gold Credit Card is designed for companies whose largest expenses change over time. It automatically earns 4X Membership Rewards points in the top two eligible categories from a defined list each billing cycle, on up to $150,000 in combined eligible purchases per calendar year, then 1X. Categories currently include U.S. purchases for advertising in select media, electronic goods retailers and software or cloud-system providers, restaurants, gas stations, transit, and wireless telephone service purchased directly from U.S. providers. The card also earns 3X on flights and prepaid hotels booked through Amex Travel and 1X elsewhere. Its $375 annual fee can be partly offset by up to $240 in annual Flexible Business Credits, divided monthly and subject to eligible merchants and enrollment, plus up to $155 in Walmart+ credits under current terms. The adaptive bonus structure is valuable for a growing business, but the category list excludes many common expenses, credits are restrictive, and the high welcome-offer spending requirement may be inappropriate for a smaller operation.
American Express® Business Gold Card Facts Table
| Feature | Details |
| Credit Card Issuer | American Express National Bank |
| Payment Network | American Express |
| Reward Type | Business Rewards Credit Card |
| Recommended Credit | Good Credit Score to Excellent Credit Score (690-850) |
| Annual Fee | $375 |
| Rewards Program | American Express Membership Rewards® |
| Welcome Offer | Apply and find out your offer; publicly advertised offers may be as high as 200,000 points after $15,000 in eligible purchases within 3 months |
| 4X Rewards | Top 2 eligible categories each billing cycle |
| 4X Annual Cap | First $150,000 in combined qualifying purchases each calendar year |
| Travel Rewards | 3X on eligible flights and prepaid hotels through American Express Travel |
| Other Purchases | 1X point |
| Employee Business Gold Card Fee | Current fee-bearing employee Gold cards available; no-fee Business Expense employee cards also available |
| Intro APR | None |
| Pay Over Time APR | 17.74%–28.49% variable |
| Penalty APR | 29.99% variable |
| Foreign Transaction Fee | None |
| Late Payment Fee | $39 or 2.99% of any past-due Pay In Full amount, whichever is greater |
| Returned Payment Fee | Up to $39 |
| Preset Credit Limit | No Preset Spending Limit |
| Pay Over Time | Yes, for eligible charges up to applicable Pay Over Time Limit |
| Flexible Business Credit | Up to $240 annually after enrollment |
| ChatGPT Business Credit | Up to $300 annually after enrollment |
| Squarespace Credit | Up to $150 annually after enrollment |
| Walmart+ Credit | Up to $12.95 plus applicable local tax monthly |
| Potential Listed Annual Credits | Up to approximately $845 |
| Cell Phone Protection | Up to $800 per approved claim; up to 2 claims per 12 months; $50 deductible |
| Purchase Protection | Up to $1,000 per covered purchase; up to $50,000 per calendar year |
| Extended Warranty | Up to 1 additional year on eligible warranties of 5 years or less |
| Rental Car Protection | Secondary Car Rental Loss and Damage Insurance |
| Baggage Insurance | Yes, on qualifying covered travel |
| Hotel Benefits | The Hotel Collection |
| Airport Lounge Access | None |
| QuickBooks Integration | Yes |
| Employee Spending Controls | Yes |
| Amex Offers | Yes |
| Best For | Businesses with large, changing operating expenses in the card’s eligible 4X categories |
Why the American Express® Business Gold Card Ranks Tenth
Business Gold ranks tenth because it can be exceptionally productive for the right company but is easy to overbuy. A business that places $100,000 of qualifying annual expenses into its two leading 4X categories could earn 400,000 Membership Rewards points before other spending, a return that can dwarf the $375 fee when points are redeemed well. A freelancer or microbusiness spending mainly on rent, taxes, insurance, or contractors may earn far less because those categories generally do not receive 4X. The credits also should be valued according to existing purchases, not their advertised maximum. Business Gold makes the top ten for its automatic category adjustment and high cap, but Blue Business Plus is the safer starting point for many smaller businesses because it has no annual fee and rewards uncategorized expenses more consistently.
10 Best Rated American Express Credit Cards in 2026 Comparison Table
| Credit Card | Intro Offer | Reward Rate | Annual Fee | Intro APR | Regular APR |
| American Express® Gold Card | Personalized offer; verify application | 1X–5X points | $325 | None | Variable Pay Over Time APR; see application |
| Blue Cash Preferred® Card from American Express | As high as $300 cash back after $3,000 in 6 months; offer varies | 1%–6% cash back | $0 first year, then $95 | 0% for 12 months on purchases and eligible balance transfers | 19.49%–28.49% variable |
| The Platinum Card® from American Express | Personalized offer; verify application | 1X–5X points | $895 | None | Variable Pay Over Time APR; see application |
| Blue Cash Everyday® Card from American Express | As high as $200 cash back after $2,000 in 6 months; offer varies | 1%–3% cash back | $0 | 0% for 15 months on purchases and eligible balance transfers | 19.49%–28.49% variable |
| American Express® Green Card | Personalized offer; verify application | 1X–3X points | $150 | None | Variable Pay Over Time APR; see application |
| Hilton Honors American Express Aspire Card | Current offer varies; verify application | 3X–14X Hilton points | $550 | None | Variable APR; see application |
| Marriott Bonvoy Brilliant® American Express® Card | Current offer varies; verify application | 2X–6X Marriott points | $650 | None | Variable APR; see application |
| Delta SkyMiles® Reserve American Express Card | Current offer varies; verify application | 1X–3X miles | $650 | None | Variable APR; see application |
| Blue Business® Plus Credit Card from American Express | 15,000 points after $3,000 in 3 months | 1X–2X points | $0 | 0% for 12 months on purchases | 17.99%–25.99% variable |
| American Express® Business Gold Card | As high as 200,000 points after $15,000 in 3 months; offer varies | 1X–4X points | $375 | None | Variable Pay Over Time APR; see application |
How to Choose the Best American Express Credit Card for Your Spending
Start with twelve months of actual spending rather than the card’s marketing page. Total purchases in the relevant categories, apply each reward rate and cap, estimate a conservative redemption value, then subtract the annual fee and any extra costs created by benefit use. Statement credits should receive full value only when they replace purchases the applicant would make anyway; a $10 monthly credit is worth little if using it requires a $30 order that would not otherwise happen. Frequent diners and U.S. supermarket shoppers should compare Gold with Blue Cash Preferred, while fee-averse households should test Blue Cash Everyday. Travelers should decide whether they value flexible points and broad lounges or are loyal enough to justify a Hilton, Marriott, or Delta card. Business owners should separate eligible company expenses from personal ones and compare the $50,000 Blue Business Plus cap with Business Gold’s specialized $150,000 4X cap. Finally, anyone expecting to carry debt should prioritize the intro APR and payoff schedule over rewards, because interest can overwhelm even a generous earning rate.
American Express Personal Credit Cards Versus American Express Business Credit Cards
Personal American Express cards are intended for consumer spending, while business cards are designed for legitimate business expenses made by a qualifying owner or company. A sole proprietor, freelancer, independent contractor, or formal company may potentially qualify for a business card, but the application should accurately describe the business and its revenue. Business cards can offer employee cards, year-end summaries, account-management tools, and categories such as advertising, software, wireless service, or shipping-related purchases. They may also differ from personal cards in consumer protections and credit-reporting behavior, so applicants should read the agreement rather than assume the rules are identical. A business card is not a workaround for personal welcome-offer restrictions and should not be used to disguise household expenses. Owners who qualify can still combine personal and business Membership Rewards cards, subject to program terms, to earn across both budgets while keeping accounting records clean.
How to Apply or Check for American Express Credit Card Preapproval
Visit the official American Express product page, review the current offer and rates-and-fees disclosure, and use the issuer’s application or preapproval experience rather than an unverified link. American Express states on many consumer card pages that an applicant can learn whether the application is approved without an initial effect on the credit score; if approved, choosing to accept the card can result in information being reported to credit bureaus and may affect the score. The applicant should provide accurate identity, housing, employment, income, and business information as requested, and should capture the exact welcome offer displayed before acceptance because personalized offers can differ. Preapproval or an approval-without-initial-impact experience is not a guarantee of final account opening, a specific credit limit, or a permanent lack of credit impact. Applicants should also avoid submitting several speculative applications in a short period and should confirm they can complete any welcome-offer spending requirement through normal, budgeted purchases.
What Credit Score Is Needed for an American Express Credit Card?
American Express does not publish a universal minimum credit score that guarantees approval for these ten cards. They are generally marketed to applicants with good to excellent credit, but a score is only one part of underwriting. Payment history, utilization, age of accounts, recent inquiries, income, debt obligations, requested product, existing American Express exposure, and information in the application can all influence the result. A commonly used FICO definition places good credit from 670 to 739, very good from 740 to 799, and exceptional from 800 upward, but those bands are educational rather than Amex approval cutoffs. Someone preparing to apply should check reports for errors, pay every account on time, reduce revolving balances where practical, avoid unnecessary new applications, and verify that the card’s annual cost fits the budget. No article or prequalification result can promise an approval, interest rate, spending capacity, or credit limit.
American Express Credit Card Annual Fees, Prices and Break-Even Value
The annual prices in this ranking range from $0 for Blue Cash Everyday and Blue Business Plus to $895 for Platinum. Price alone does not determine value: a $650 hotel card can be economical for a loyal guest who uses a high-value annual certificate and credits, while a $95 cash-back card can be wasteful for a shopper who spends little in its bonus categories. Calculate break-even value by converting rewards and genuinely useful credits to dollars, then subtracting the annual fee, foreign transaction fees, financing charges, and any extra spending needed to unlock benefits. For example, Blue Cash Preferred’s 6% supermarket rate provides a three-percentage-point advantage over a 3% no-fee alternative on the first $6,000 of eligible annual supermarket spending; that advantage can reach $180, more than its ongoing $95 fee. Premium-card calculations require more caution because lounge visits, status, and monthly credits are subjective. Never count a credit at face value when it expires unused or changes established buying behavior.
Best American Express Credit Card for Cash Back in 2026
The Blue Cash Preferred Card is the best cash-back choice in this ranking for households that can use its U.S. supermarket, U.S. streaming, transit, and U.S. gas station categories. Its 6% supermarket return on up to $6,000 per year is especially compelling, and the first-year $0 introductory annual fee makes the initial value equation favorable for many eligible applicants. Blue Cash Everyday is the better alternative when annual spending is lower, online retail is more important, or the user strongly prefers no annual fee. Cash back should be compared after category caps, merchant coding, and the ongoing $95 fee, and the cardholder should avoid carrying interest-bearing debt. Gold may produce more travel value for some shoppers, but its Membership Rewards points are not the same as fixed cash back and require a different redemption strategy.
Best American Express Credit Card for Balance Transfers in 2026
Blue Cash Everyday is the best balance-transfer option among these ten cards because it offers 0% intro APR for 15 months on eligible balance transfers requested within 60 days of account opening, followed by a 19.49%–28.49% variable APR under the terms reviewed for this article. A transfer fee of either $5 or 3% of each transfer, whichever is greater, applies, and balances generally cannot be transferred from another account issued by the same institution. Blue Cash Preferred is the runner-up with a shorter 12-month 0% period and the same stated transfer-fee structure. The correct strategy is to divide the transferred balance plus fee by the number of promotional months, set automatic payments above that amount when affordable, and stop adding unaffordable purchases. If the debt remains when the introductory period ends, the variable APR can materially increase the payoff cost, so rewards should be secondary to the repayment plan.
Best American Express Credit Card for International Travel in 2026
The Platinum Card is the best American Express card in this ranking for frequent international travelers who can use its broad lounge access, premium hotel program, transfer partners, travel credits, protections, and lack of foreign transaction fees. Gold is a better value for many travelers who prioritize worldwide restaurants and transferable points but do not need lounges, while Green offers broad travel and transit rewards for a lower annual fee. Hilton Aspire and Marriott Brilliant can be superior for trips concentrated within their respective hotel ecosystems. International travelers should still carry a no-foreign-transaction-fee Visa or Mastercard as a backup because American Express is not accepted everywhere, and they should pay in local currency when a merchant offers an unfavorable dynamic currency conversion. Travel benefits also have eligibility and payment requirements, so the card used to book the trip should be selected with both rewards and insurance terms in mind.
Final Verdict on the 10 Best Rated American Express Credit Cards in 2026
The American Express Gold Card is the best overall choice for a rewards-focused consumer who spends heavily at restaurants and qualifying U.S. supermarkets, values transfer partners, and can naturally use its credits. Blue Cash Preferred is the strongest cash-back card, Platinum leads premium travel, and Blue Cash Everyday is the best no-fee and balance-transfer option. Green gives travelers a moderate-fee Membership Rewards path, while Hilton Aspire, Marriott Brilliant, and Delta Reserve are worthwhile only when brand loyalty makes their certificates, status, lounges, credits, and baggage benefits genuinely useful. Blue Business Plus is the most broadly accessible business value because it earns 2X on varied expenses up to its cap without an annual fee; Business Gold is the more powerful but specialized choice for higher spending in eligible categories. The best final decision is the card with the highest conservative net value after fees, not the product with the flashiest bonus. Confirm all live terms on the linked official company page on the day of application.