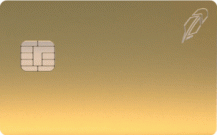

The Robinhood Gold Credit Card is one of the most unusual premium cash-back credit cards available in 2026 because it combines a simple 3% cash-back rate across eligible purchase categories with direct integration into the broader Robinhood investment ecosystem. Offered by Robinhood Credit, Inc. and issued by Coastal Community Bank on the Visa network, the card charges no separate annual card fee but generally requires an active annual Robinhood Gold membership, currently priced at $50 per year for most eligible applicants. The defining feature is straightforward: qualifying purchases earn 3% cash back without the rotating categories, quarterly activation requirements, or complicated spending bonuses common among competing rewards cards. That rewards structure makes the Robinhood Gold Card especially compelling for consumers who spend heavily across many categories and who already use Robinhood for investing, retirement accounts, cryptocurrency trading, or cash management. Unlike dedicated cryptocurrency credit cards such as Gemini, Coinbase One, or Crypto.com, the Robinhood Gold Card does not directly pay card rewards in Bitcoin or another cryptocurrency; instead, points can be converted into brokerage cash and deposited into an eligible Robinhood investing account, where the cardholder can decide how those funds are subsequently invested.
- Flat 3% Rewards
- No Category Tracking
- $0 Card Annual Fee
- No Authorized User Fee
- Brokerage Cash Redemption
- Effective Annual Membership Cost
- Not a Pure Crypto Rewards Card
- Robinhood Ecosystem Requirement
- No Publicly Highlighted Intro APR
- No Traditional Large Welcome Bonus
Favorable Details
- Flat 3% Rewards: One of the biggest advantages of the Robinhood Gold Card is the ability to earn 3% on eligible purchases across categories rather than only receiving the highest rate on dining, groceries, gas, or travel.
- No Category Tracking: Cardholders do not have to activate quarterly bonus categories or remember which merchants qualify for different percentages.
- $0 Card Annual Fee: The underlying card does not charge a conventional annual fee.
- No Authorized User Fee: The account can accommodate authorized users without a recurring authorized-user charge, although upgraded physical card materials may involve separate fees when available.
- Brokerage Cash Redemption: Rewards can be converted at a value of one cent per point into cash deposited directly into a Robinhood investing account.
- Investment Flexibility: After rewards are redeemed as brokerage cash, users can decide whether to keep the money as cash or invest it through Robinhood according to available products and account eligibility.
- Crypto-Adjacent Flexibility: Consumers interested in cryptocurrency can use separately available funds within the Robinhood ecosystem to obtain eligible crypto exposure rather than being locked into a specific reward coin.
- Virtual Card Features: Digital card numbers and disposable card functionality can provide additional privacy and security for online purchases.
- Family Card Controls: Robinhood allows cardholders to add additional users and manage spending controls from the app.
- Metal Card Construction: The standard Gold Card has been marketed with a stainless-steel construction weighing approximately 17 grams, giving the card a premium physical feel without a separate card annual fee.
- Visa Network Acceptance: The card benefits from broad Visa acceptance in the United States and internationally where Visa credit cards are accepted.
- Trip Interruption Protection: Applicable Visa benefits may include trip interruption protection subject to coverage terms, exclusions, and eligibility requirements.
- Preapproval Without Immediate Credit Impact: Robinhood advertises the ability for eligible consumers to see whether they are approved without initially affecting their credit score, with credit impact occurring if the offer is accepted.
- Simple Rewards Math: Because the principal earning rate is 3%, calculating expected rewards is easier than with complicated tiered or rotating-category cards.
Unfavorable Details
- Effective Annual Membership Cost: Even though the Gold Card itself has a $0 annual fee, most cardholders need a $50 annual Robinhood Gold subscription, meaning the product is not completely free to maintain.
- Not a Pure Crypto Rewards Card: Consumers specifically looking to earn Bitcoin automatically should consider a dedicated cryptocurrency credit card instead.
- Robinhood Ecosystem Requirement: The card provides its greatest value to users willing to maintain both Robinhood Gold and an eligible brokerage relationship.
- No Publicly Highlighted Intro APR: Consumers seeking 0% financing for a large purchase may find stronger options elsewhere.
- No Traditional Large Welcome Bonus: The card’s core appeal is its ongoing 3% reward rate rather than a large introductory cash bonus.
- Rewards Terms Can Change: Cash-back program rules and redemption options may be modified over time.
- Potentially High Ongoing APR: As with most rewards cards, the regular variable APR can make carrying debt expensive.
- No Transferable Travel Points: The card does not provide airline or hotel transfer partners like premium travel cards from Chase, American Express, Capital One, or Citi.
- Limited Luxury Travel Positioning: The Gold Card is primarily a cash-back and investment-focused product rather than a premium lounge-access or luxury-travel card.
- Investment Risk After Redemption: Once rewards are invested in stocks, ETFs, cryptocurrency, or other market assets, those funds can decline in value.
Robinhood Gold Card Facts Table
| Features | Details |
| Credit Card Platform | Robinhood Credit, Inc. |
| Credit Card Issuer | Coastal Community Bank |
| Payment Network | Visa® |
| Rewards Type | Cash Back Reward Points |
| Recommended Credit | Good Credit to Excellent Credit Score (690-850) |
| Annual Fee | $0 |
| Standard Rewards Rate | 3% cash back on eligible purchases |
| Point Value for Brokerage Cash | $0.01 per point |
| Robinhood Gold Membership | Generally required; $50 annual subscription for most eligible applicants |
| Authorized User Fee | $0 for standard authorized users |
| Standard Card Material | Stainless steel |
| Standard Card Weight | Approximately 17 grams |
| Intro Purchase APR | No standard 0% promotional offer prominently highlighted |
| Regular APR | Variable APR according to approved account terms |
| Foreign Transaction Fee | Review current account pricing before travel |
| Rewards Redemption | Brokerage cash and other eligible redemption options |
| Brokerage Account Requirement | Required to redeem rewards as brokerage cash |
| Preapproval | Approval may be checked without initial credit-score impact |
| Best For | Robinhood users seeking 3% flat-rate rewards |
Robinhood Gold Card Welcome Offer
The Robinhood Gold Card is not primarily positioned around a traditional large sign-up bonus. Instead, its long-term value comes from the ongoing 3% cash-back rate available on eligible purchases. This approach differs from many traditional rewards cards that attract new customers with $200, $300, or larger introductory bonuses but then provide lower long-term rewards. Consumers deciding whether the Robinhood Gold Card is worthwhile should therefore focus more heavily on their expected annual spending, the value of Robinhood Gold membership, and how consistently they can take advantage of the card’s 3% rate.
Robinhood Gold Card Rewards Rate
The headline feature of the Robinhood Gold Card is 3% cash back across eligible purchase categories, making it one of the strongest flat-rate consumer credit-card reward structures in the market. A cardholder who places $20,000 of qualifying annual purchases on the card could theoretically generate approximately $600 in rewards before accounting for membership costs or excluded transactions, while $40,000 in annual eligible spending could produce approximately $1,200 in rewards. Because the earning rate does not depend on restaurant, grocery, gas, or travel categories, the card is particularly attractive to consumers whose spending is distributed across many merchant types.
How the Robinhood Gold Card Works
The Robinhood Gold Card functions like a conventional revolving credit card issued by Coastal Community Bank. Cardholders use the Visa network to make purchases, qualifying transactions generate rewards points, and those points can subsequently be redeemed through Robinhood’s card ecosystem. Rewards can be converted into brokerage cash and deposited into an eligible Robinhood investing account at a value of one cent per point. The cardholder can then decide whether to retain those funds as cash or use them within Robinhood’s broader investment platform, subject to account eligibility and available investment products.
3% Cash Back Across Eligible Categories
A flat 3% reward rate is exceptionally strong because most no-annual-fee or low-cost cards earn approximately 1.5% to 2% on general purchases while reserving higher percentages for selected categories. Robinhood eliminates much of that complexity by paying 3% on eligible purchases without requiring a cardholder to optimize spending categories. That can make the Gold Card especially valuable for expenses such as insurance, home improvement, medical bills, general retail purchases, subscriptions, electronics, utilities, professional services, and other transactions that often earn only a base rate on competing cards.
Brokerage Cash Rewards
Robinhood allows eligible points to be converted to brokerage cash at approximately one cent per point and transferred into a Robinhood investing account. This feature is especially useful for consumers who already use Robinhood because rewards can become investable funds without requiring a separate bank transfer. The money remains cash at the point of redemption, however, so it should not be confused with direct stock or cryptocurrency rewards.
Robinhood Gold Card and Cryptocurrency
The Robinhood Gold Card is often included in cryptocurrency-card comparisons because Robinhood operates a large cryptocurrency trading platform, but the Gold Card itself does not directly earn Bitcoin or another cryptocurrency. Cardholders earn cash-back points, which can be redeemed as brokerage cash. After the cash reaches an eligible Robinhood investing account, the consumer can independently decide how to use those funds according to the products and investment choices available to them. This flexibility can actually be an advantage for consumers who do not want every reward automatically converted into cryptocurrency at the market price prevailing when each transaction posts.
Robinhood Gold Membership Requirement
Most applicants need an active annual Robinhood Gold subscription to obtain and retain the Robinhood Gold Card. The annual subscription currently costs $50 for Gold Card members and does not include the ordinary 30-day Gold free trial associated with some other Robinhood membership offers. Certain consumers applying through specific partner channels may be exempt from the membership requirement, but the typical applicant should treat $50 as an effective annual cost when comparing the Gold Card against competing no-annual-fee cash-back cards.
Effective Annual Fee
Although the Robinhood Gold Card technically advertises a $0 annual card fee, the required Gold membership means most consumers should think of the product as carrying an effective annual cost of approximately $50. A cardholder earning 3% on $10,000 of annual eligible spending would receive around $300 in rewards before considering the membership cost, leaving approximately $250 in net reward value if the consumer assigns no separate value to the other Gold benefits. Someone already paying for Robinhood Gold for investment features, however, may effectively view the card’s incremental annual cost as zero.
Robinhood Gold Membership Benefits Beyond the Card
Robinhood Gold provides benefits outside the credit card, and these can materially change the overall value calculation. Depending on current program terms, Gold membership may provide enhanced yield opportunities on eligible brokerage cash, IRA contribution incentives, investment research features, margin-related benefits, and other premium Robinhood services. Consumers who already value these services may find it easier to justify the membership requirement, while users interested only in credit-card rewards should compare the $50 subscription cost with competing cards that require no membership.
High-Yield Cash Integration
Eligible Robinhood Gold members may earn a competitive annual percentage yield on qualifying brokerage cash through Robinhood’s available high-yield cash program. The yield can change with market conditions and program rules, but this feature creates an additional use case for Gold Card rewards because brokerage cash transferred from points can potentially earn interest when enrolled and eligible. Cardholders should remember that an APY is variable and should not be treated as a permanent guaranteed rate.
No Authorized User Fee
Robinhood currently advertises no standard authorized-user fee on the Gold Card. This can make the account attractive for households that want to centralize spending and rewards without paying an additional annual fee for each family member. Authorized users generally receive a plastic card at no cost, while an upgraded stainless-steel card may carry a separate one-time charge if offered.
Family Card Features
The Robinhood Gold Card includes unusually flexible family-spending functionality. Primary cardholders can add additional cardholders, monitor spending, create limits, and lock cards through the Robinhood app. These features can help households manage spending centrally while potentially earning 3% rewards on qualifying purchases made by additional users.
Virtual Cards and Disposable Card Numbers
Digital security is one of the Robinhood Gold Card’s stronger differentiators. Robinhood provides virtual card functionality and has promoted disposable card numbers for online transactions. These features can reduce the need to expose the physical card number at every online merchant and may provide additional convenience when making subscription or e-commerce purchases.
Stainless-Steel Card Design
The Robinhood Gold Card is marketed as a stainless-steel Visa weighing approximately 17 grams. Metal construction does not increase the financial value of a rewards card, but consumers who prefer premium physical cards may appreciate receiving a metal product without paying the several-hundred-dollar annual fee typically associated with many premium travel cards.
Visa Benefits
The Robinhood Gold Card operates on the Visa network and includes applicable card-network benefits subject to current terms and eligibility requirements. Robinhood specifically highlights trip interruption protection, while other Visa-related protections may depend on the exact benefit guide attached to the account. Consumers should review the current Visa benefits disclosure before relying on a particular insurance or purchase-protection feature.
Trip Interruption Protection
Trip interruption protection can reimburse certain qualifying prepaid travel expenses when a covered trip is disrupted by an eligible event. The exact coverage limits, exclusions, documentation requirements, and eligible events depend on the Visa benefit terms attached to the Robinhood Gold Card, so cardholders should not assume every canceled or interrupted trip is covered.
Robinhood Gold Card APR
The Robinhood Gold Card uses a variable purchase APR based on approved account terms and broader interest-rate conditions. Because the card’s primary advantage is a 3% reward rate, carrying a balance can quickly eliminate its economic benefit. Even a relatively short period of interest at typical credit-card APR levels can cost significantly more than the rewards generated by the underlying purchase.
Introductory APR
Robinhood does not currently emphasize a long 0% introductory purchase APR as a core Gold Card feature. Consumers who plan to finance a large purchase over 12 to 21 months may receive more value from a dedicated 0% intro APR card even if that card has a lower rewards rate.
Balance Transfers
The Robinhood Gold Card is not marketed primarily as a balance-transfer credit card. Consumers carrying high-interest debt should generally prioritize cards offering extended 0% balance-transfer periods rather than choosing a rewards card solely for cash back.
Cash Advances
Cash advances should generally be avoided because they may carry transaction fees, potentially higher APRs, and immediate interest charges. Cash advances and other cash-equivalent transactions may also be excluded from earning rewards.
Credit Score and Approval Requirements
Robinhood and Coastal Community Bank do not guarantee approval based on a single published credit score. Underwriting can consider credit history, income, existing debt, payment history, utilization, account history, and other factors. Consumers with established good or excellent credit profiles may be more competitive applicants, but a particular FICO score does not guarantee acceptance.
Robinhood Gold Card Preapproval
One useful application feature is Robinhood’s ability to show eligible applicants whether they are approved without initially affecting their credit score. Robinhood states that the consumer’s credit will not be affected unless the applicant chooses to accept the offered card. This can reduce the uncertainty associated with applying blindly for a rewards card, although consumers should still review all terms before accepting.
Does the Robinhood Gold Credit Card Build Credit?
The Robinhood Gold Card is a conventional revolving credit account, so responsible use can contribute to a cardholder’s overall credit profile. Paying on time, maintaining low utilization, and keeping the account in good standing can support healthy credit management, while late payments, high balances, or default can negatively affect credit.
Rewards Redemption
Robinhood points can be redeemed through available options within the Robinhood ecosystem, with brokerage cash representing one of the most important choices. Brokerage cash redemption currently values points at approximately one cent each. Consumers should compare available redemption methods before using points because certain options may provide different convenience or restrictions.
Using Rewards for Investing
Once points have been converted into brokerage cash, the consumer controls how those funds are used subject to Robinhood account terms. This can make the Gold Card an attractive automated investing tool because ordinary spending generates rewards that can be deposited into an investment account. Investors should nevertheless recognize that investing redeemed rewards introduces market risk that does not exist when cash rewards are simply deposited into a checking or savings account.
Robinhood Gold Card vs. Direct Crypto Rewards Credit Cards
The Robinhood Gold Card differs from dedicated cryptocurrency rewards cards because it provides cash-back points instead of automatically depositing Bitcoin or another digital asset. Crypto-focused consumers may actually appreciate this flexibility because they can decide when and whether to invest rewards instead of receiving crypto at the market price on each transaction. Consumers who want completely automatic Bitcoin accumulation may prefer Gemini, Coinbase One, Fold, or another direct crypto card.
Robinhood Gold Card vs. Gemini Credit Credit Card®
The Robinhood Gold Card is stronger for general spending because it earns 3% on eligible purchases across categories, while the Gemini Credit Card generally earns 1% on miscellaneous purchases but offers higher rates in selected categories such as dining and transportation. Gemini’s principal advantage is direct cryptocurrency rewards, while Robinhood Gold provides cash-back points that can later be directed into an investing account. Consumers wanting maximum flat-rate rewards may prefer Robinhood, while those who want automatic Bitcoin or altcoin rewards may prefer Gemini.
Robinhood Gold Card vs. Nexo Credit Card vs. Coinbase One Credit Card
Coinbase One focuses on direct Bitcoin rewards and can provide higher rates for consumers maintaining substantial qualifying assets on Coinbase, while Robinhood Gold provides a simple 3% cash-back rate without tying the percentage to an investment-balance tier. Coinbase One can be more attractive for dedicated Bitcoin investors who already use Coinbase extensively, while Robinhood Gold is likely more versatile for consumers who want broad investment flexibility and strong rewards across virtually every qualifying purchase category.
Robinhood Gold Card vs. Crypto.com Visa Signature® Credit Card
The Crypto.com Visa Signature Credit Card can produce higher headline cryptocurrency rewards for customers participating in upper Level Up tiers, but the system is more complicated and can involve subscriptions, CRO exposure, and spending thresholds. Robinhood Gold uses a much simpler 3% flat-rate approach. Crypto.com is stronger for consumers who specifically want Bitcoin or CRO rewards and already participate deeply in the Crypto.com ecosystem, while Robinhood Gold is more straightforward for consumers who want predictable cash-back rewards and broader investment flexibility.
Robinhood Gold Card vs. Fold Bitcoin Credit Card™
Fold is centered specifically on Bitcoin and provides a base BTC earning structure with opportunities to increase rewards through additional qualifying Bitcoin activity. Robinhood Gold instead pays 3% cash-back points on eligible purchases without requiring the user to receive Bitcoin. Fold is therefore better suited to dedicated Bitcoin accumulators, while Robinhood Gold is potentially superior for consumers who want a higher simple general reward rate and control over when, whether, and how those rewards are invested.
Robinhood Gold Card vs. Venmo Credit Card
The Venmo Credit Card provides category-based cash-back rewards and can support automatic cryptocurrency purchases through Venmo’s Cash Back to Crypto functionality, whereas Robinhood Gold pays a flat 3% on eligible purchases. Robinhood is easier to optimize because consumers do not need to identify their highest spending category, while Venmo can appeal to users who want a mainstream payment app and optional crypto conversion without maintaining a Robinhood investment account.
Robinhood Gold Card vs. PayPal Cashback Mastercard® Credit Card
The PayPal Cashback Mastercard earns higher rewards on qualifying PayPal purchases and a lower rate on general transactions, while Robinhood Gold offers 3% broadly across eligible categories. Heavy PayPal users may receive strong value from PayPal’s elevated checkout rate, but Robinhood’s flat structure can be more rewarding for purchases made outside PayPal. Both cards integrate closely with larger financial ecosystems, making the choice partly dependent on whether the consumer prefers Robinhood investing or PayPal payments.
Robinhood Gold Card vs. Traditional 2% Cash-Back Credit Cards
Traditional 2% cash-back cards remain formidable competitors because many charge no annual fee and require no paid membership. Robinhood’s extra 1 percentage point of rewards can overcome the $50 Gold subscription relatively quickly. If a consumer spends $5,000 annually on eligible purchases, the additional 1% over a 2% card equals approximately $50, effectively offsetting the membership cost. Consumers spending considerably more than $5,000 per year may therefore generate meaningful incremental value from Robinhood’s 3% rate, assuming they would not otherwise pay for Robinhood Gold.
Robinhood Gold Card vs. Premium Travel Credit Cards
Premium travel cards often provide airport lounge access, transferable airline points, hotel benefits, statement credits, and travel protections that Robinhood Gold does not emphasize. The Robinhood Gold Card instead prioritizes simplicity and cash-back value. Consumers who travel frequently and know how to maximize transferable points may receive more value from a premium travel card, while users who dislike complicated travel programs may prefer Robinhood’s straightforward 3% structure.
Who Should Get the Robinhood Gold Card?
The Robinhood Gold Card is best suited to consumers who already use Robinhood, value Robinhood Gold membership, consistently pay credit-card balances in full, and spend enough annually to benefit from a 3% flat reward rate. It can be especially attractive to investors who want cash-back rewards automatically integrated into a brokerage environment and consumers whose purchases do not fit neatly into traditional dining, grocery, gas, or travel bonus categories.
Who Should Avoid the Robinhood Gold Card?
Consumers who do not want a Robinhood Gold membership, prefer traditional bank rewards, carry revolving credit-card debt, want automatic cryptocurrency rewards, or need a long 0% introductory APR may find better options elsewhere. Low spenders should also calculate whether the incremental reward advantage over a free 2% cash-back card is sufficient to justify the $50 Gold subscription.
Is the Robinhood Gold Card Worth It?
The Robinhood Gold Card can provide exceptional value for the right consumer because a 3% flat reward rate is difficult to match without significant category restrictions. The economics become especially attractive for consumers who already pay for Robinhood Gold because the card itself adds no separate annual fee. Even consumers joining Gold primarily for the card can potentially offset the $50 annual membership relatively quickly through additional rewards compared with a conventional 2% card. The biggest caveats are ecosystem dependence, the absence of direct crypto rewards, no major introductory APR promotion, and the importance of paying balances in full.
Frequently Asked Questions About the Robinhood Gold Card
The Robinhood Gold Card generates considerable interest because its 3% flat reward rate is unusually high for a consumer credit card. The key points are that the card itself has no annual fee, Robinhood Gold membership is generally required, qualifying purchases earn 3% cash back, rewards can be redeemed into a Robinhood brokerage account, and the card is issued by Coastal Community Bank on the Visa network.
Does the Robinhood Gold Card Have an Annual Fee?
The credit card itself currently has no annual fee, but most applicants need an active Robinhood Gold membership, which currently costs $50 annually for Gold Card members.
Does the Robinhood Gold Card Really Earn 3% Cash Back?
Yes. Robinhood currently advertises 3% cash back across eligible purchase categories, subject to rewards-program rules, exclusions, and other applicable conditions.
Is Robinhood Gold Membership Required?
Generally yes. The card is designed for Robinhood Gold members, although Robinhood states that certain eligible consumers applying through particular partner channels may not be subject to the membership requirement.
Does the Robinhood Gold Card Earn Bitcoin?
No. The card earns cash-back points rather than Bitcoin directly. Cardholders can redeem eligible points as brokerage cash and then decide how to use those funds within the Robinhood ecosystem.
Can Robinhood Gold Card Rewards Be Invested?
Yes. Eligible rewards can be converted into brokerage cash and deposited into a Robinhood investing account, after which the account holder can determine how to use those funds.
What Is the Robinhood Gold Card Point Value?
Brokerage cash redemptions currently value Robinhood Gold Card points at approximately one cent per point.
What Bank Issues the Robinhood Gold Card?
The Robinhood Gold Card is issued by Coastal Community Bank and offered through Robinhood Credit, Inc.
Is the Robinhood Gold Card Visa or Mastercard?
The Robinhood Gold Card operates on the Visa network.
Does the Robinhood Gold Card Have Authorized User Fees?
Robinhood currently advertises no standard authorized-user fee. Authorized users generally receive plastic cards, while optional stainless-steel upgrades may cost extra when available.
Does Applying Affect Your Credit Score?
Robinhood states that eligible applicants can see whether they are approved without affecting their credit score initially. Credit impact can occur if the applicant chooses to accept the card offer.
Does the Robinhood Gold Card Have a 0% Intro APR?
Robinhood does not currently promote a standard extended 0% introductory purchase APR as one of the Gold Card’s primary features.
Is the Robinhood Gold Card Good for Cryptocurrency Investors?
It can be, particularly for investors who want the flexibility to receive cash-back rewards and later choose their investments rather than having rewards automatically paid in cryptocurrency. Dedicated crypto cards remain more appropriate for consumers who want direct Bitcoin or token rewards.
Final Verdict
The Robinhood Gold Credit Card is one of the strongest flat-rate cash-back credit cards available in 2026 for consumers already participating in the Robinhood ecosystem. Its headline 3% cash-back rate on eligible purchases is exceptionally competitive and eliminates much of the category management required by traditional rewards cards. The card also benefits from a $0 separate annual card fee, no standard authorized-user fee, stainless-steel construction, virtual and disposable card features, Visa acceptance, family spending controls, trip interruption protection, and direct redemption of rewards into an eligible Robinhood investment account. The principal tradeoff is the Robinhood Gold membership requirement, which currently costs most cardholders $50 annually, along with the lack of a prominent introductory 0% APR and the fact that rewards are cash back rather than direct cryptocurrency. For consumers who already subscribe to Robinhood Gold, the card can be extremely difficult to beat because the 3% earning rate effectively comes without an additional card fee. For consumers joining solely to obtain the card, spending levels should be compared with a conventional 2% cash-back alternative to determine whether the membership cost is justified. Investors who want complete flexibility over whether their rewards ultimately remain cash, purchase stocks, fund other investments, or contribute to eligible cryptocurrency exposure may find the Robinhood Gold Card especially compelling.